Written Commentary
CORN
Prices closed $.07-$.10 higher while spreads also firmed. To see a push above today’s highs we’ll likely need to see a more threatening forecast in South America, or some demand interest from China. Baseline projections show US farmers will plant 95.5 mil. acres of corn in 2027, down from 96.8 mil. this year. The USDA announced a flash sale of 312.7k tons of corn to Mexico.
- US production was cut 141 mil. bu. to 15.893 bil., 70 mil. below expectations
- The Ave. US yield was cut 1.6 bpa to 179.6 bpa with no changes to harvested acres
- Yields were down 10 bpa in MI, 8 in IL, 5 bpa in IN and MO while down 4 in NE. Yields rose 9 bpa in MN
- 2026/27 ending stocks were cut 91 mil. to 1.758 bil. 82 mil. below expectations
- 2026/27 usage was cut 50 mil. bu. with exports and feed usage both down 25 mil.
- The Ave. Farm Price was cut $.10 to $4.60 bu.
- Global stocks in 2026/27 up 1.5 to 282 mmt, in line with expectation
SOYBEANS
Higher to sharply higher prices across the complex with beans up $.30-$.40, meal was $5-$7 higher while oil is up 65-75 points. While we are not in a rationing situation right now, the lower US production and stocks outlook does make it critical South American achieves trendline yields. Crush margins were crushed another $.20 to $1.81 bu., a new 10 month low. Chinese soybean imports from all sources in October at 7.35 mmt was down 22.5% YOY. YTD imports at 93.5 mmt are down 2.2%. The USDA Baseline projections show US farmers will plant 87.5 mil. acres of soybeans in 2027, up from 86.9 mil. this year. US harvest advanced only 4% to 92% complete, vs. the 5-year Ave. of 91%, also behind expectations. The USDA announced a flash sale of 150k tons of soybeans to Mexico. Light rain is expected across the Great Lakes region and ECB the next 24-48 hours, otherwise dry across Midwest through the end of the week. This should enable harvest to wrap up in a timely manner. Weather in SA remains non-threatening.
- US production rose 12 mil. bu. to 4.574 bil., 23 mil. below expectations
- The Ave. US yield was increased .3 bpa to 53.3 bpa with no changes to harvested acres
- Yields were cut 4 bpa in IL and 3 bpa in KS. Yields rose 5 bpa in MN, 3 bpa in SD and NE while up 2 in IA
- 2026/27 ending stocks were cut 15 mil. to 300 mil. 30 mil. below expectations
- 2026/27 exports were increased 25 mil. bu.
- The Ave. Farm Price was increased $.10 to $12.10 bu.
- Global stocks in 2026/27 down nearly 1 mmt to 123.5 mmt, vs. expectations of no change
WHEAT
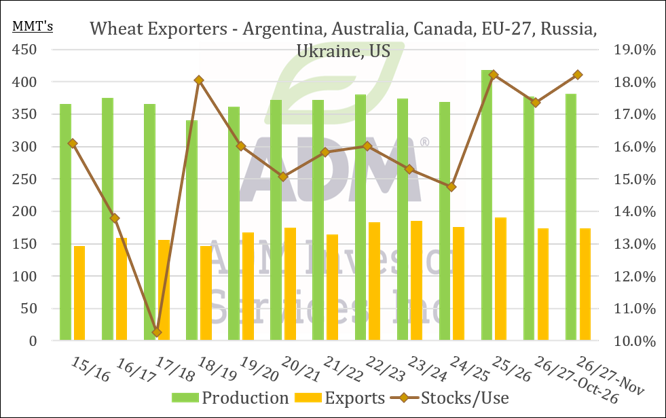
Prices ranged from $.02-$.07 higher. Not much in today’s USDA data for wheat as prices will prices will remain sensitive to developments with peace talks between US, Russia and Ukraine. Without progress on peace between Ukraine/Russia, or at least some progress reopening the Black Sea I’d expect the market to reinject War premium. US wheat acres are expected to be up 1.5 mil. in 2027 to 44 mil. according to the Baseline projections. Jordan passed on making any purchases in their 120k mt tender. US winter wheat plantings at 89% are just below the 5-year Ave. of 90%. Ratings improved 5% to 49% G/E, vs. expectations of a 2% improvement. Ratings jumped 11% in OK, 9% in TX, and 7% in CO.
- US ending stocks rose 3 mil. bu. to 743 mil. in line with expectations
- HRW stocks increased 11 mil. bu. to 344 mil. while white wheat stocks fell 10 mil. to 70 mil.
- Global production rose 5 mmt to 827.5 mmt. Argentina and Australia both up 1.5 mmt
- Global stocks increased 5 mmt to 281 mmt, vs. expectations for a 1 mmt increase
- Russia and Ukraine exports cut another 1 mmt each to 39 and 11.5 mmt respectively
Risk Warning: Investments in Equities, Contracts for Difference (CFDs) in any instrument, Futures, Options, Derivatives and Foreign Exchange can fluctuate in value. Investors should therefore be aware that they may not realise the initial amount invested and may incur additional liabilities. These investments may be subject to above average financial risk of loss. Investors should consider their financial circumstances, investment experience and if it is appropriate to invest. If necessary, seek independent financial advice.
ADM Investor Services International Limited, registered in England No. 2547805, is authorised and regulated by the Financial Conduct Authority [FRN 148474] and is a member of the London Stock Exchange. Registered office: 3rd Floor, The Minster Building, 21 Mincing Lane, London EC3R 7AG.
A subsidiary of Archer Daniels Midland Company.
© 2021 ADM Investor Services International Limited.
Futures and options trading involve significant risk of loss and may not be suitable for everyone. Therefore, carefully consider whether such trading is suitable for you in light of your financial condition. The information and comments contained herein is provided by ADMIS and in no way should be construed to be information provided by ADM. The author of this report did not have a financial interest in any of the contracts discussed in this report at the time the report was prepared. The information provided is designed to assist in your analysis and evaluation of the futures and options markets. However, any decisions you may make to buy, sell or hold a futures or options position on such research are entirely your own and not in any way deemed to be endorsed by or attributed to ADMIS. Copyright ADM Investor Services, Inc.
