Written Commentary
CORN
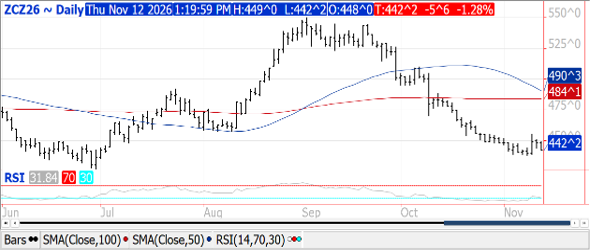
Prices were $.05 ½-$.07 ½ lower, closing near session lows. Dec-26 closed below the previous day’s low while still holding within Tuesday’s range. Speculative selling likely taking the MM short position to 30k contracts after today’s trade. Higher production est. for Brazil by the USDA continue to be absorbed by higher domestic usage. The USDA’s 141 mmt forecast for 2026/27 narrows the gap with Conab’s 148 mmt, which is expected to be updated tomorrow. While this week’s USDA report may have raised the price floor, to see Mch-27 futures push above $4.70 will likely require a more threatening forecast in South America. Ethanol production slipped to 332 mil. gallons last week, down from 336 mil. the previous week while up 5% YOY. There was 111 mil. bu. of corn used in the production process, or 15.85 mil. bu. per day, above the 15.56 mbd needed to reach the USDA forecast of 5.650 bil. bu. If last week’s pace held over the remaining 43 weeks of the MY, corn usage would reach 5.735 bil. bu. Stocks slipped to 24.3 mil. barrels, in line with expectations while well above the 22.2 mb from YA. Production margins remain firm despite a pullback in recent weeks. Tomorrow’s export sales are expected to range from 75-115 mil. bu.
SOYBEANS
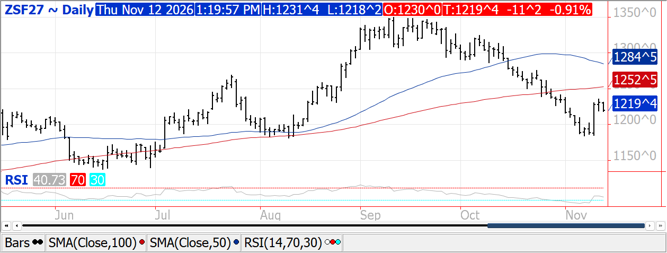
Prices were lower across the complex with beans down $.12-$.15, meal was off $3-$4 while oil was down 40-45 points. Jan-27 beans also just traded below yesterday’s low. Resistance above the market is at the 100-day MA at $12.52 ½. Spot meal and oil both failed to trade above yesterday’s high, setting up today’s pullback. The USDA announced a flash sale of 136k mt (5 mil. bu.) of soybeans to China, perhaps some disappointment sales weren’t larger. Crush margins for now have leveled off near $1.95 bu. with bean oil PV staying close to 49.5%. With the lower-than-expected US production and stocks there is less wiggle room for South American yields to come in below trend. Brazilian planting are approaching 75% while just underway in Argentina, so a lot of growing season ahead. Conab to update Brazilian production tomorrow. China purchases likely sitting around 20 mmt. With the USDA raising US exports 25 mil. to 1.720 bil. bu. this week (46.8 mmt), leaves only 21.8 mmt to non-Chinese buyers, after China wraps up their 25 mmt purchases. That would be down 25% from YA. Despite the higher US soybean exports, this week’s WASDE and Baseline data continue to illustrate the growth in US soybean crush, while exports remain well below record levels. This week’s exports are expected to range from 35-70 mil. bu. for soybeans, 250-450k tons of meal and 0-10k oil.
WHEAT
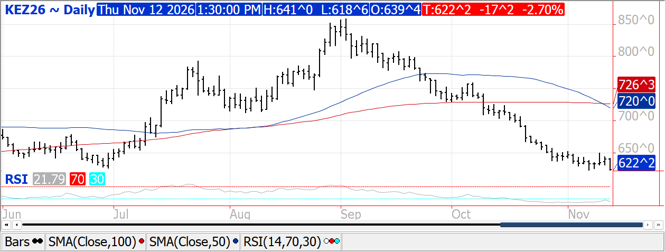
Prices ranged from $.13 to $.17 lower across the 3 classes as another round of tri-lateral peace talks weighed on prices. Dec-26 CGO was down $.15 ¼ at $5.84 ¼, Dec-26 KC was $.17 ¼ lower at $6.22 ¼ while Dec-26 MIAX was off $.12 ¾ at $6.22 ¾. Higher global stocks support the recent price selloff however continued supply disruptions from the Black Sea region may reverse that trend. US wheat has become more competitive in the global marketplace. Algeria bought around 700k mt of wheat near $313/mt CF. Much of the grain is believed to be sourced from Argentina with smaller volumes from the Baltic Sea area (Russia) along with Bulgaria and Romania. Export sales are expected to range from 12-24 mil. bu. Updated WASDE data showed combined ME and N. Africa production at 46.4 mmt up 26% from YA which enabled their combined imports to slip to 46.4 mmt, down 18% YOY and the lowest in 6 years.
Risk Warning: Investments in Equities, Contracts for Difference (CFDs) in any instrument, Futures, Options, Derivatives and Foreign Exchange can fluctuate in value. Investors should therefore be aware that they may not realise the initial amount invested and may incur additional liabilities. These investments may be subject to above average financial risk of loss. Investors should consider their financial circumstances, investment experience and if it is appropriate to invest. If necessary, seek independent financial advice.
ADM Investor Services International Limited, registered in England No. 2547805, is authorised and regulated by the Financial Conduct Authority [FRN 148474] and is a member of the London Stock Exchange. Registered office: 3rd Floor, The Minster Building, 21 Mincing Lane, London EC3R 7AG.
A subsidiary of Archer Daniels Midland Company.
© 2021 ADM Investor Services International Limited.
Futures and options trading involve significant risk of loss and may not be suitable for everyone. Therefore, carefully consider whether such trading is suitable for you in light of your financial condition. The information and comments contained herein is provided by ADMIS and in no way should be construed to be information provided by ADM. The author of this report did not have a financial interest in any of the contracts discussed in this report at the time the report was prepared. The information provided is designed to assist in your analysis and evaluation of the futures and options markets. However, any decisions you may make to buy, sell or hold a futures or options position on such research are entirely your own and not in any way deemed to be endorsed by or attributed to ADMIS. Copyright ADM Investor Services, Inc.
