Written Commentary
CORN
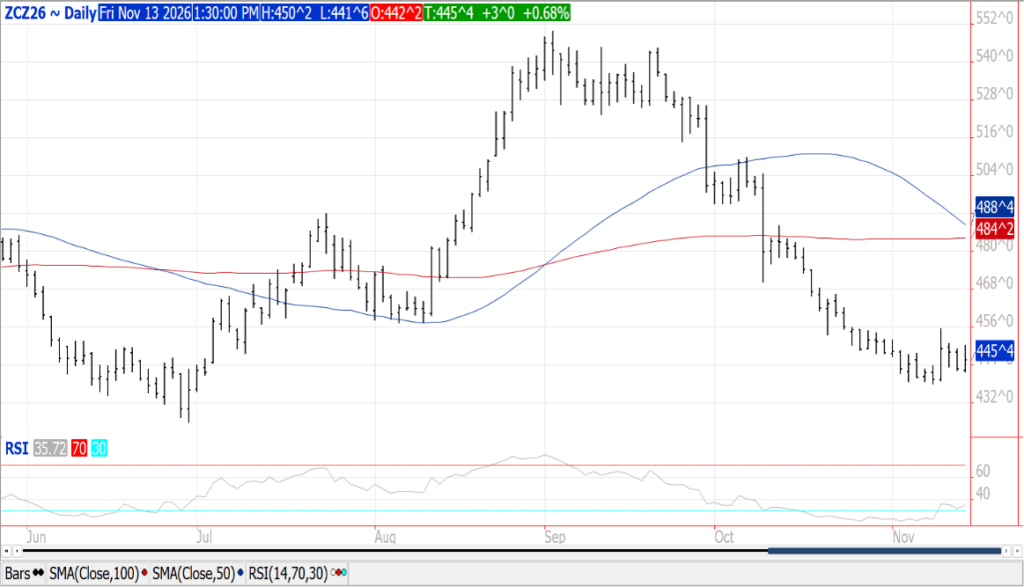
Prices were $.01-$.03 higher as spreads firmed. Dec-26 closed near the midpoint of today’s range in choppy 2-sided trade. Yesterday’s O.I. was up another 12.3k contracts despite heavy liquidation of the Dec-26 contract. Conab kept their Brazilian production forecast unchanged at 148 mmt, however lowered their export forecast 3 mmt, shifting more demand to domestic uses. The USDA raised their forecast this week 2 mmt to 141 mmt. The gap between the USDA and SA production forecasts narrowed this week, however, remain significant. US export sales at 136 mil. bu. (113 mil. – 26/27 MY, 23 mil. – 27/28) were above expectations. Old crop sales were a MY high however YTD commitments are still down 28% YOY vs. the revised USDA forecast of down 4.5%. Mexico bought 77 mil. bu. of old crop, while also accounting for all of the new crop sales. The USDA also announced a flash sale of 303.3k tons of corn to Mexico with 272.8k tons for 26/27 MY, the balance for 27/28. Ukraine’s corn exports as of Nov. 13th at 2.42 mmt are down 5.5% from YA. This week’s USDA data raised the price floor however for Mch-27 to trade and hold above $4.75 will likely require a more threatening forecast in SA.
SOYBEANS
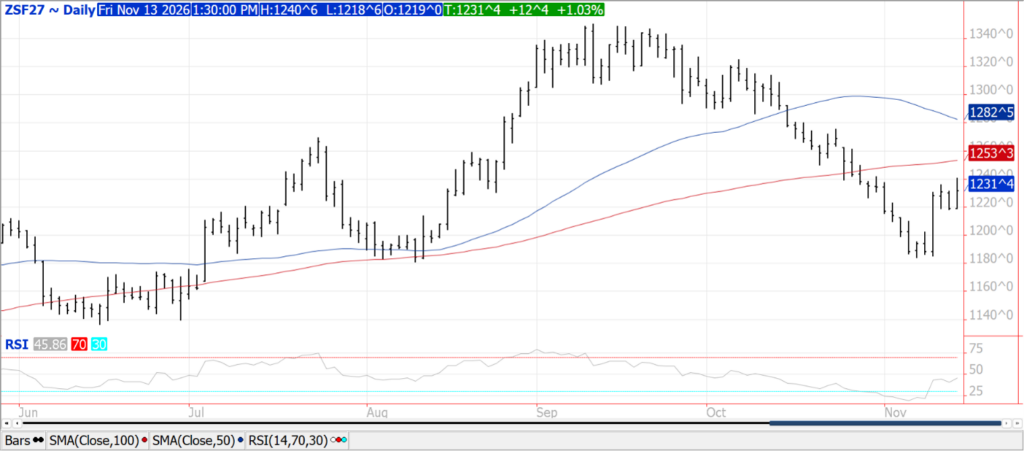
Prices were higher across the complex with beans up $.12-$.13, meal was $3-$4 higher while oil was up 35-40 points. Bean and meal spreads firmed while oil spreads were mixed. Jan-27 beans stretched out to a new high for the month with next resistance is the 100-day MA at $12.53 ½. Dec-26 meal also jumped up to a new high for the month. Dec-26 oil traded to a new high for the week. Russian missile attacks forced Ukraine to suspend operations at 2 major sunflower oil processing plants causing further damage to their agricultural economy. Conab held their Brazilian production forecast unchanged at 181.6 mmt, vs. the USDA est. of 186 mmt. The lower US production and stocks leaves little wiggle room for South American yields to come in below trend. Brazilian plantings are approaching 70% while just underway in Argentina, so a lot of growing season ahead. US exports at 42 mil. was at the low end of expectations. YTD commitments are up 78% from YA vs. the revised USDA forecast of up 13.5%. Known commitments to China are at 16.637 mmt with another 5.37 mmt to unknown. The USDA also announced several flash sales with 134k mt to China, 120k mt to Vietnam and 100k mt to unknown. YTD meal commitments are up 2.5% YOY vs. the USDA forecast up 12%. YTD bean oil sales are down 78% vs. the USDA forecast of down 59%. With the USDA raising US exports 25 mil. to 1.720 bil. bu. (46.8 mmt), this leaves only 21.8 mmt to non-Chinese buyers, down 25% from YA vs. the current pace of down 13.6%. Ahead of Pres. Trump meeting with Chinese leader Xi next week on the sidelines of the APEC summit, the ASA has called on the Trump Administration to cut their 10% fentanyl tariff on Chinese imports, to encourage China to cut their 10% reciprocal tariff.
WHEAT
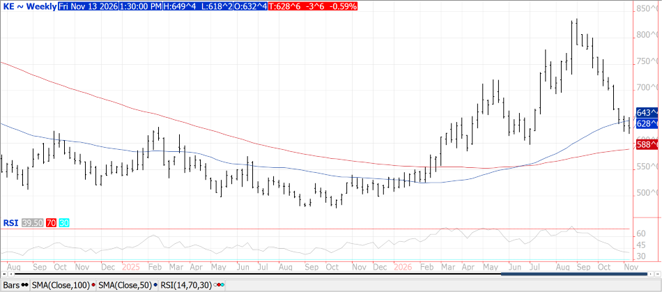
Prices finished up $.04-$.09 across the 3 classes, well off session highs. The Spot price for KC wheat has now been lower for 11 consecutive weeks. Today’s rebound would suggest the market is less confident a 2nd round of tri-lateral peace talks will result in the reopening the Black Sea. Ukraine’s wheat exports as of Nov. 13th at 4.11 mmt are down 39% YOY. Russian grain exports via seaports in Oct-26 reached 2.8 mmt, off 56% vs. YA. YTD shipments for the 26/27 MY at 9 mmt are down 54%. Conab lowered their Brazilian production forecast .5 mmt to 5.26 mmt, vs. the USDA est. of 5.8 mmt. Higher global stocks support the recent price selloff however continued supply disruptions from the Black Sea region may reverse that trend. US exports at 7 mil. bu. was a MY low. YTD commitments are down 29% from YA vs. the USDA forecast of down 17%. The RGE raised their Argentine production forecast .5 mmt to 24.3 mmt, vs. the USDA est. of 23 mmt. US winter wheat area in drought held steady this week at 48%.
Risk Warning: Investments in Equities, Contracts for Difference (CFDs) in any instrument, Futures, Options, Derivatives and Foreign Exchange can fluctuate in value. Investors should therefore be aware that they may not realise the initial amount invested and may incur additional liabilities. These investments may be subject to above average financial risk of loss. Investors should consider their financial circumstances, investment experience and if it is appropriate to invest. If necessary, seek independent financial advice.
ADM Investor Services International Limited, registered in England No. 2547805, is authorised and regulated by the Financial Conduct Authority [FRN 148474] and is a member of the London Stock Exchange. Registered office: 3rd Floor, The Minster Building, 21 Mincing Lane, London EC3R 7AG.
A subsidiary of Archer Daniels Midland Company.
© 2021 ADM Investor Services International Limited.
Futures and options trading involve significant risk of loss and may not be suitable for everyone. Therefore, carefully consider whether such trading is suitable for you in light of your financial condition. The information and comments contained herein is provided by ADMIS and in no way should be construed to be information provided by ADM. The author of this report did not have a financial interest in any of the contracts discussed in this report at the time the report was prepared. The information provided is designed to assist in your analysis and evaluation of the futures and options markets. However, any decisions you may make to buy, sell or hold a futures or options position on such research are entirely your own and not in any way deemed to be endorsed by or attributed to ADMIS. Copyright ADM Investor Services, Inc.
