Written Commentary
CORN
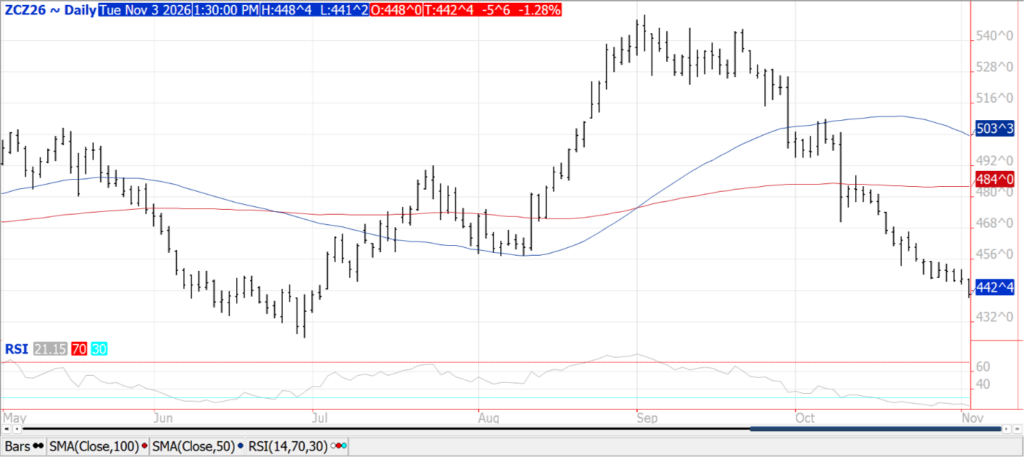
Prices were $.05-$.06 lower, closing near session lows, while spreads were mixed and little changed. Dec-26 fell to a fresh 4-month low with next support at its contract low at $4.24 ¾. Disappointing trade action considering the USDA announced a flash sale of just over 1.7 mmt of corn to Mexico yesterday, followed up with another 315k mt today and 136k mt sold to S. Korea. Mexico’s imports of US corn was the lowest in 3 years in Oct-26. There was 438 mil. bu. of corn used to produce ethanol in Sept-26, at the low end of expectations. Usage needs to average 474 mil. bu. Oct-26 through Aug-27 to reach the USDA usage forecast of 5.650 bil. bu. Harvest progress at 74% was in line with expectations and just below the 5-year Ave. of 77%. Using USDA Oct-26 production estimates there is nearly 2.2 bil. bu. left to harvest in NE, SD, MN and IA. Bulls remain hopeful US corn will be on China’s wish list however the path of least resistance remains lower until speculators stop shedding length in the corn market and/or a more threatening forecast develops in SA. Tomorrow’s EIA data is expected to show ethanol production very close to the previous week’s 329 mil. gallons, just above the pace needed to reach the USDA forecast.
SOYBEANS
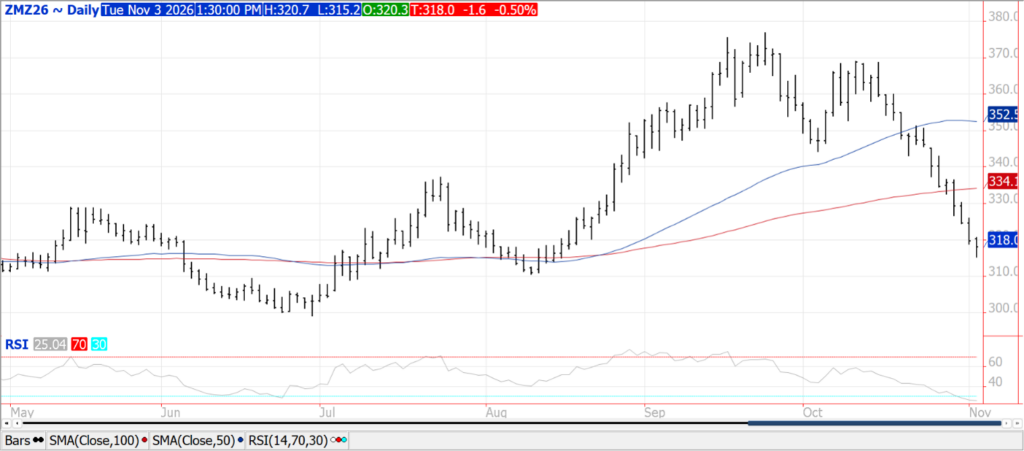
Mostly lower trade across the complex with beans off $.02-$.09, meal was $2-$5 lower while oil was steady to 15 points higher. Spreads firmed across the complex. Jan-27 beans and Dec-26 meal have both fallen to a 2 ½ month low. Dec-26 oil held support just above LW’s low at 64.50 setting up the price recovery. The USDA announced a flash sale of 134k mt (5 mil. bu.) to an unknown buyer. I estimate Chinese purchases are near 19 mmt. Yesterday’s net selling across the complex took the combined MM long position down to 373k, still historically large however below the recent record of 558k. For now, the path of least resistance is lower as speculative traders continue to shed length as SA forecasts remain non-threatening. Crush margins were little changed, holding near 9-month lows at $2.14 bu. Sept-26 crush at 199 mil. bu. was slightly below expectations. The Ave. daily processing rate at 6.63 mil. bu. per day was the lowest in 13 months, held back by harvest delays and lack of soybean supplies, particularly in the WCB. To reach the USDA forecast of 2.780 bil. bu., crush will need to average 235 mil. bu. per month Oct-26 through Aug-27. Bean oil stocks at 1.458 bil. lbs. were below expectations of 1.534 bil. Harvest progress advanced 9% to 88% complete, vs. the 5-year Ave. of 84%, also in line with expectations.
WHEAT
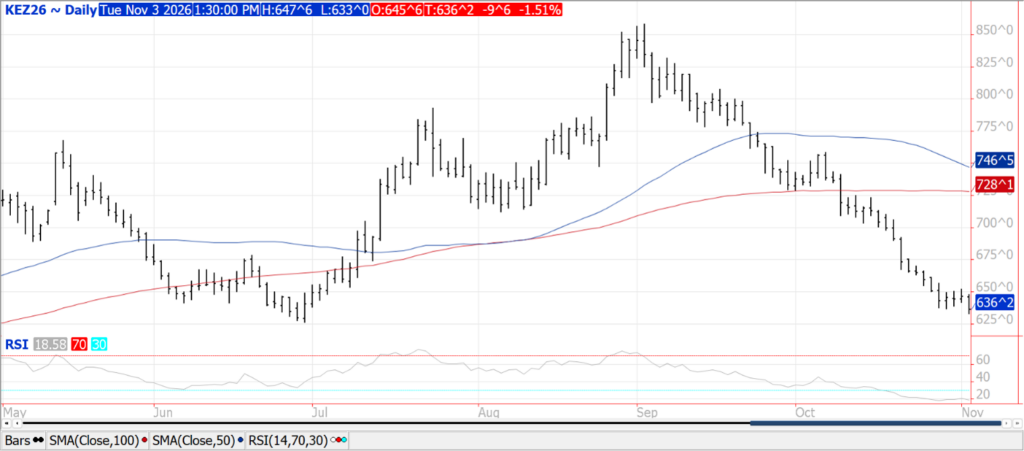
Prices were $.07-$.10 lower across the 3 classes in choppy 2-sided trade. CGO Dec-26 was $.06 ¾ lower at $5.99 ¾, Dec-26 KC was off $.09 ¾ at $6.36 ¼ while Dec-26 MIAX was down $.06 ¾ at $6.19. The US, Russia and Ukraine have agreed to host tri-lateral peace talks in the UAE on Nov. 10th and 11th. Ukraine Pres. Zelenskiy has urged all parties to discuss a ceasefire on energy infrastructure and in the Black Sea region. Prices will remain sensitive to Chinese demand interest, or lack thereof. With Russia able to ship roughly 3 mmt per month with another 1 mmt from Ukraine would put the current USDA export forecasts at 40 and 12.5 mmt respectively close to the current reality. IKAR lowered their Russian wheat export forecast 2.5 mmt to 39.5 mmt. US WW plantings at 83% are just below the 5-year Ave. of 84%. Crop ratings at 44% G/E were in line with our expectations, however well below the Ave. estimate in the Reuters poll at 50%. Rain in the S. Plains to benefit conditions before dormancy. There were only 2 participants in Jordan’s 120k mt wheat tender with no purchase being made.
Risk Warning: Investments in Equities, Contracts for Difference (CFDs) in any instrument, Futures, Options, Derivatives and Foreign Exchange can fluctuate in value. Investors should therefore be aware that they may not realise the initial amount invested and may incur additional liabilities. These investments may be subject to above average financial risk of loss. Investors should consider their financial circumstances, investment experience and if it is appropriate to invest. If necessary, seek independent financial advice.
ADM Investor Services International Limited, registered in England No. 2547805, is authorised and regulated by the Financial Conduct Authority [FRN 148474] and is a member of the London Stock Exchange. Registered office: 3rd Floor, The Minster Building, 21 Mincing Lane, London EC3R 7AG.
A subsidiary of Archer Daniels Midland Company.
© 2021 ADM Investor Services International Limited.
Futures and options trading involve significant risk of loss and may not be suitable for everyone. Therefore, carefully consider whether such trading is suitable for you in light of your financial condition. The information and comments contained herein is provided by ADMIS and in no way should be construed to be information provided by ADM. The author of this report did not have a financial interest in any of the contracts discussed in this report at the time the report was prepared. The information provided is designed to assist in your analysis and evaluation of the futures and options markets. However, any decisions you may make to buy, sell or hold a futures or options position on such research are entirely your own and not in any way deemed to be endorsed by or attributed to ADMIS. Copyright ADM Investor Services, Inc.
