Written Commentary
CORN
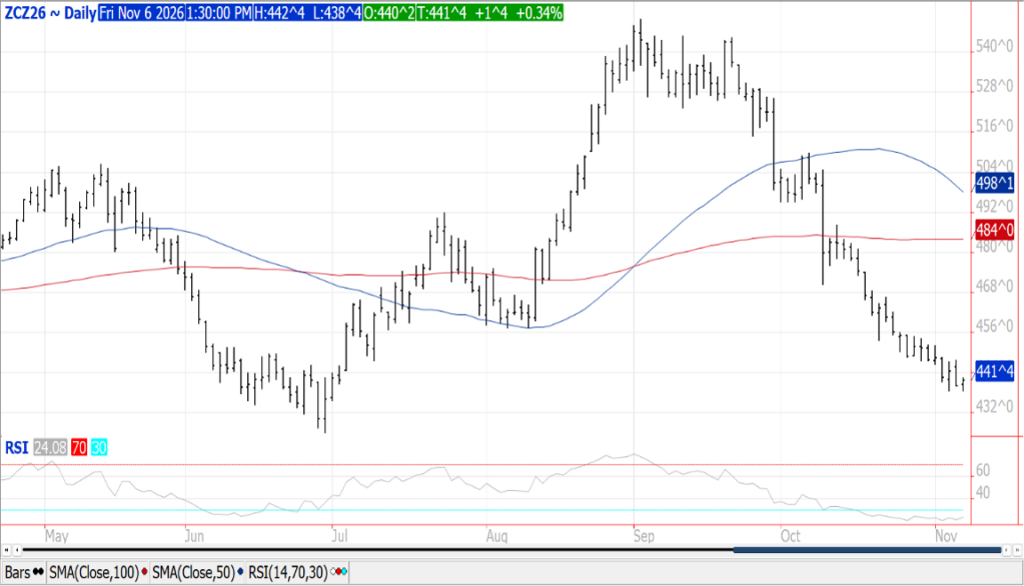
Prices were $.01-$.02 higher while spreads recovered with today being the first day of the Goldman roll. Dec-26 held support at this week’s low at $4.38 ½. Speculative traders sold 12k contracts yesterday, reducing their long position to 51k. Open interest was up just over 18k contracts. They were likely light buyers in today’s trade. The Ave. production est. in the Reuters poll at 15.962 bil. bu. is down 72 mil. bu. from the USDA Oct-26 est. Ending stocks are expected to fall only 9 mil. bu. to 1.840 bil. The pattern of lower corn yields in August and September followed by higher yields in October has happened only 5 times since 1990. In all 5 years yields were up again in Nov. The USDA announced a flash sale of 101k mt (4 mil. bu.) of corn to an unknown buyer. China’s Commerce Minister has suggested additional purchases of US Ag. goods hinges on both sides implementing a $60 bil. reciprocal tariff-cut agreement. The 2 sides are expected to meet to discuss tariff cuts before the end of the year. The BAGE reports corn plantings in Argentina have reached 51%, well above their historical average.
SOYBEANS
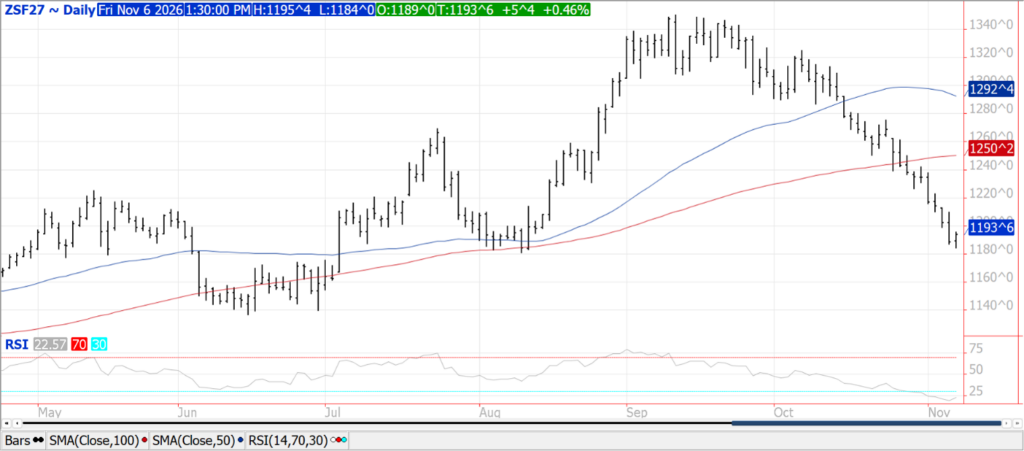
A late recovery enable prices to close steady to higher across the complex. Beans were steady to $.05 higher. Jan-27 beans avoided closing lower for 10th consecutive session. Meal was $1-$2 higher while a late recovery in oil enabled prices to close steady to 10 higher. Dec-26 oil recovered after falling to an 8-month low while also violating support at a 50% retracement level near 61.50. Meal gained on oil this week as the US looks to gain market share into EU next year as EUDR (deforestation regulation) becomes law requiring larger EU importers to verify soybean and soybean meal imports came from land not deforested after Dec-2020. With diesel prices just off their record highs while D4 RIN’s hover just below $2, this week’s selloff in soybean oil triggered a surge in RD profit margins. Yesterday’s net selling across the complex took the combined MM long position down to 342k, below the recent record of 558k. Speculative traders have continued to shed length as SA forecasts remain mostly non-threatening. The Ave. production est. in the Reuters poll at 4.597 bil. bu. is up 35 mil. bu. from the USDA forecast in Oct-26. Ending stocks are expected to rise 16 mil. bu. to 331 mil. Bean exports are up 76% from YA vs. the USDA forecast of up 12%. The USDA announced a flash sale of 136k mt (5 mil. bu.) to China. Their total purchases are likely between 19-19.5 mmt.
WHEAT
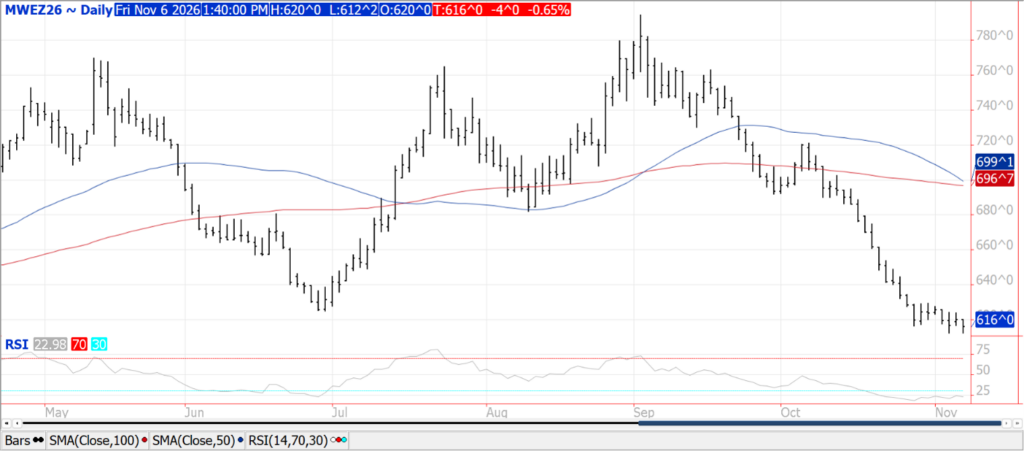
Prices ranged from $.03-$.08 lower. Both CGO and KC closed off session lows while MIAX established a new contract low. Prices were pressured by Pres. Trump suggesting next week’s peace talks in the UAE between US, Russia, and Ukraine could result in a cease-fire with a peace agreement that includes all of Europe. Recent monthly export flows of 3-3.5 mmt of wheat shipped from Russia and another 1 mmt from Ukraine annualized are quite close to the current USDA forecasts of 40 mmt from Russia and 12.5 mmt from Ukraine. US winter wheat areas in drought fell 2% to 48% while spring wheat areas in drought fell 4% to 34%. The UN’s FAO reports that world food prices slipped 1.2% in October however are still up 6% YOY.
Risk Warning: Investments in Equities, Contracts for Difference (CFDs) in any instrument, Futures, Options, Derivatives and Foreign Exchange can fluctuate in value. Investors should therefore be aware that they may not realise the initial amount invested and may incur additional liabilities. These investments may be subject to above average financial risk of loss. Investors should consider their financial circumstances, investment experience and if it is appropriate to invest. If necessary, seek independent financial advice.
ADM Investor Services International Limited, registered in England No. 2547805, is authorised and regulated by the Financial Conduct Authority [FRN 148474] and is a member of the London Stock Exchange. Registered office: 3rd Floor, The Minster Building, 21 Mincing Lane, London EC3R 7AG.
A subsidiary of Archer Daniels Midland Company.
© 2021 ADM Investor Services International Limited.
Futures and options trading involve significant risk of loss and may not be suitable for everyone. Therefore, carefully consider whether such trading is suitable for you in light of your financial condition. The information and comments contained herein is provided by ADMIS and in no way should be construed to be information provided by ADM. The author of this report did not have a financial interest in any of the contracts discussed in this report at the time the report was prepared. The information provided is designed to assist in your analysis and evaluation of the futures and options markets. However, any decisions you may make to buy, sell or hold a futures or options position on such research are entirely your own and not in any way deemed to be endorsed by or attributed to ADMIS. Copyright ADM Investor Services, Inc.
