Written Commentary
CORN
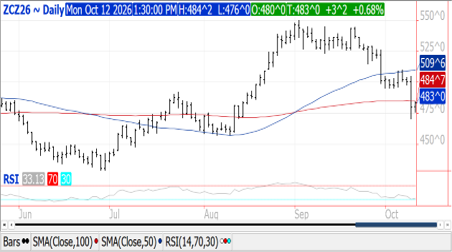
Prices were $.01-$.03 higher while spreads firmed. Dec-26 held within Friday’s range while its rally attempt was capped at the 100-day MA. Support below Friday’s low is at the August low of $4.63. Friday’s CFTC data showed MM’s were net sellers of just over 60k contracts, reducing their long holdings to 317k. After huge selling on Friday, I estimate that long position is back under 238k contracts, a 2-month low. Many remain skeptical of the USDA 2.7 bpa increase in the Ave. corn yield to 181.2 bpa, particularly in the WCB following record heat this summer. Completely baffling is NE where yields shot up 11 bpa to 188 bpa. Nevertheless, now the function of the market now is to find a price level that stimulates demand. China is well behind the pace needed to reach $17 bil. (prorated in 2026) in Ag. purchases outside the 25 mmt commitment for soybeans. APK-Inform lowered their Ukraine’s production forecast 1.5% to 31.8 mmt, matching the USDA est. I suspect US harvest has advanced to around 38%-40%. Farmer selling has dried up since Friday’s price break. Since 1990 the USDA lower yields in Aug and Sept, only to raise them in Oct. 4 times, with this year being the 5th. Three times the final yield was above the October forecast, while 1 year the final yield was unchanged from Oct. Friday’s WASDE data showed global stocks among major exporting countries rose to 11.8% of usage for the 25/26 MY, the highest in 7 years. Global stocks in 26/27 at 10.6% were up from 9.3% in Sept-26.
SOYBEANS
Prices across the complex were mixed with beans down $.03-$.04, meal ranges from steady to up $3 while oil was 50-60 points higher. Bean spreads were mixed while product spreads firmed. Support for Nov-26 soybeans is at its 50-day MA at $12.68. Dec-26 meal stretched out to a 2-week high. Dec-26 oil has MA resistance between $.69-$.6925 lbs. Crush margins have jumped $.18 to $2.78 ½ bu., the highest in 3-months. Remnants of Hurricane Isaias brought widespread rains to the SE US, otherwise harvest was wide open across the central Midwest. A narrow, but heavy line of showers is expected to pull from the SW plains into the central Midwest by mid-week, slowing harvest progress. The SE US will continue to dry out. Week 2 of the outlook remains favorable for harvest. Friday’s CFTC data showed MM’s were net buyers of 10.5k contracts of soybeans, 11.6k contracts of oil while selling 612 contracts of meal extending their combined long position to a record 558k contracts. This has likely fallen to 535k by Friday’s close. Chinese purchases have slowed since late Sept-26 which we estimate are very close to 15 mmt. China’s Sinograin is expected to auction off another 513k mt of soybeans tomorrow. Patria AgroNegocios reports Brazilian plantings are at a record pace at 20%, vs. 13% YA and the 5-year Ave. of 11.6%. US harvest is likely approaching 50%. Malaysian palm oil stocks surged 24.5% in Sept. to a record 3.51 mmt as production rose 16.5% to 2.12 mmt. Since 1990 the USDA lowered yields in Oct, only to raise them in Sept and October 5 times, with this year being the 6th. In the previous 5 years the final yield was above the October forecast 3 times, while below it twice. Stocks/use among major exporting countries fell to 19.1% in 2025/26 MY down from 19.3%, while 2026/27 held steady to 18.5%, the lowest in over a decade.
WHEAT
Prices were mixed ranging from $.04 lower to $.01 higher. CGO Dec-26 is up $.01 ¼ at $6.72 ¼, Dec-26 KC was down $.04 at $7.15 ¼ while Dec-26 MIAX was up $.01 at $6.96 ¼. All held within Friday’s range. Shortly after Pres. Trump announced there was an energy ceasefire between Ukraine/Russia, Ukraine Pres. Zelenskyy claimed Russia has already violated the agreement. Baltic countries are urging the EU to block the movement of Russian grain through the region to access ports along the Baltic Sea. IKAR raised their Russian Oct-26 export forecast .5 mmt to 3 mmt. They also report their export price ended last week at $268/mt, up $2 from the previous week. MM’s were net sellers of 19k contracts combined across the 3 classes of wheat, reducing their net-long position to only 6k contracts, the smallest in 3 months. Global stocks/use among major exporting countries jumped to 17.3% in October from 15.5% from Sept. on rising stocks in Russia and lower usage estimates. With the recent price pullback IMO there is little “War Premium” left in the market. Unless the Black Sea opens soon, I sense downside price risk is limited.
Risk Warning: Investments in Equities, Contracts for Difference (CFDs) in any instrument, Futures, Options, Derivatives and Foreign Exchange can fluctuate in value. Investors should therefore be aware that they may not realise the initial amount invested and may incur additional liabilities. These investments may be subject to above average financial risk of loss. Investors should consider their financial circumstances, investment experience and if it is appropriate to invest. If necessary, seek independent financial advice.
ADM Investor Services International Limited, registered in England No. 2547805, is authorised and regulated by the Financial Conduct Authority [FRN 148474] and is a member of the London Stock Exchange. Registered office: 3rd Floor, The Minster Building, 21 Mincing Lane, London EC3R 7AG.
A subsidiary of Archer Daniels Midland Company.
© 2021 ADM Investor Services International Limited.
Futures and options trading involve significant risk of loss and may not be suitable for everyone. Therefore, carefully consider whether such trading is suitable for you in light of your financial condition. The information and comments contained herein is provided by ADMIS and in no way should be construed to be information provided by ADM. The author of this report did not have a financial interest in any of the contracts discussed in this report at the time the report was prepared. The information provided is designed to assist in your analysis and evaluation of the futures and options markets. However, any decisions you may make to buy, sell or hold a futures or options position on such research are entirely your own and not in any way deemed to be endorsed by or attributed to ADMIS. Copyright ADM Investor Services, Inc.
