Written Commentary
CORN
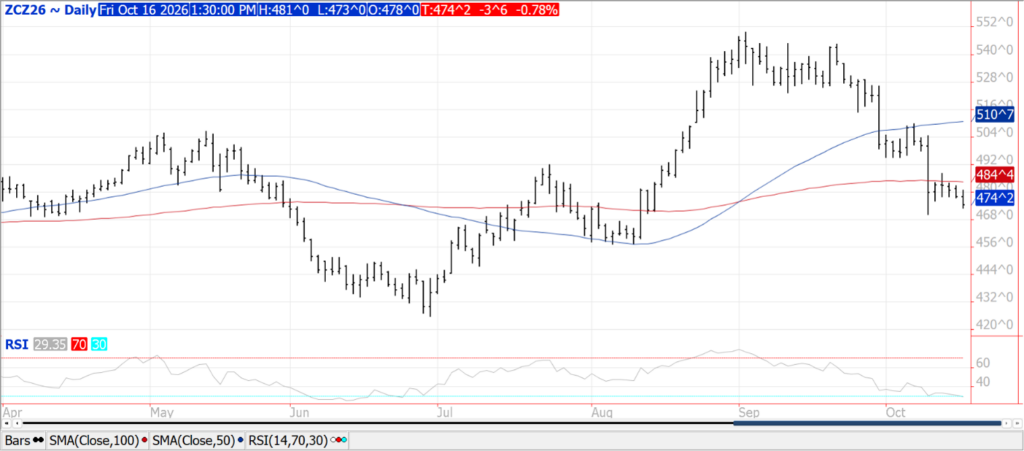
Prices were $.03 ½ – $.04 ½ lower while spreads firmed a bit. Dec-26 slumped to a new low for the week however has held support above LW’s low near $4.70 with secondary support at $4.57 ¼. Yesterday’s open interest fell 5.4k contracts. Conab is projecting Brazil’s 2026/27 production at 148 mmt, well above the USDA’s 139 mmt forecast. The BAGE pegs Argentine plantings at 35%, well ahead of their normal pace. Corn harvest in France has reached 92%. Exports sales at 44 mil. bu. was in line with expectations and a MY high. YTD commitments are still down 33% from YA vs. the revised USDA forecast of down 4%. Commitments represent 25% of the USDA est. vs. the historical average of 34%. Noted buyers were Mexico – 21.5 mil. bu., Japan – 9 mil. while 8 mil. to Korea. The USDA also announced a flash sale of 127k tons (5 mil. bu.) to Japan.
SOYBEANS
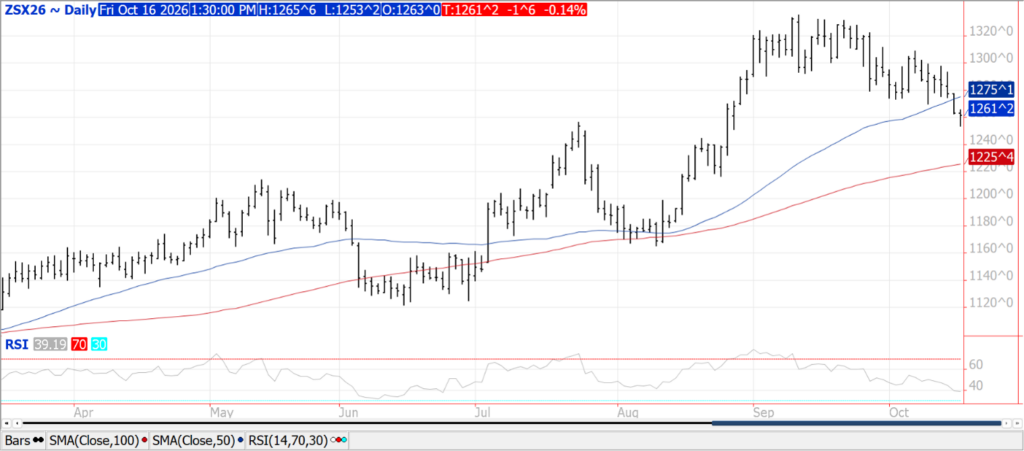
Lower closes across the complex with beans down $.02-$.03, meal was off $2-$3 while oil was off a few points. The soybean market largely shrugged off another round of flash soybean sales to China and unknown. A favorable harvest forecast combined with speculators shedding length in the agricultural markets has left the path of least resistance to the downside. Nov-26 beans slipped to a fresh 7-week low however bounced before reaching $12.50. Longer term support is at the 100-day MA at $12.25 ½. Support for Dec-26 meal is at its 50-day MA, currently $348. Inside trade for Dec-26 oil. Open interest from yesterday’s trade was up 3.2k contracts in soybeans, 4k in soybean meal while down a couple hundred contracts in oil. Crush margins were down $.04 at $2.63 bu. Export sales at 21 mil. was at the low end of expectations. YTD commitments are up 74% from YA vs. the revised USDA forecast of up 12%. Commitments to China are at 11.27 mmt as of Oct. 8th with another 5.64 mmt to unknown. Best guess on sales to China as of Oct. 8th stood at roughly 14.5 mmt. The USDA announced additional flash sales of 558k mt to China and 236k to unknown. Announced sales this week likely take commitments to China up to 16-16.5 mmt. If China’s 25 mmt of soybean purchases is already reflected in the current USDA export forecast of 1.695 bil. bu.(46.1 mmt) then sales to non-Chinese buyers must slip to 21 mmt, down 27% YOY. Current commitments to non-Chinese buyers at 430 mil. bu. are down only 13%. I’m leaning toward the current export forecast still too low. Meal sales at 366k tons were in line with expectations. YTD commitments are up 6% vs. the USDA forecast of up 11%. D4 RIN’s generated in September at 788.1 mil. were up 10% from August, however, fell further behind the level needed to reach the RFS mandates.
WHEAT
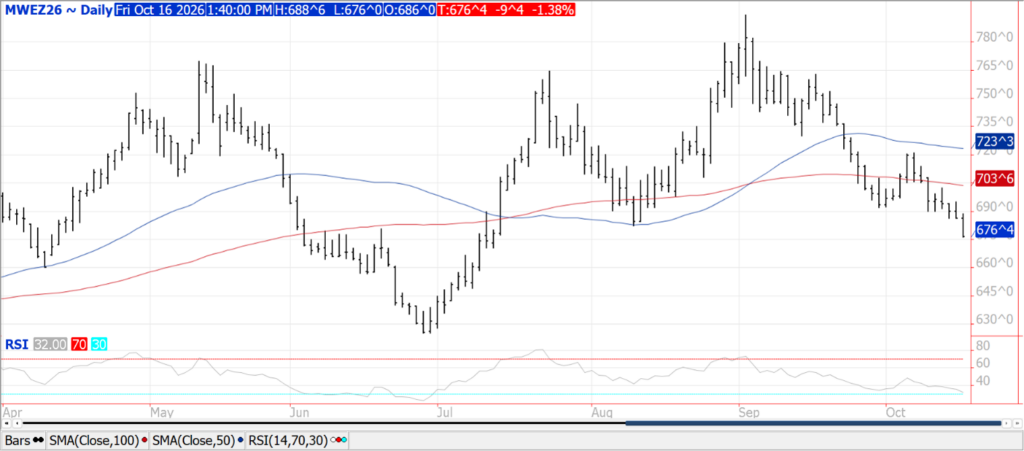
Prices closed $.09-$.10 lower across the 3 classes. CGO Dec-26 slipped to a fresh 2 ½ month low with next support at the August low near $6.45. Dec-26 KC barely held support above the $7.00 level. Dec-26 MIAX closed into a 3-month low. This afternoon’s CFTC report will likely show MM’s back to being net short wheat for the first time in 3 months. Western Australia production is expected to reach 10.9 mmt, up from last month’s forecast of 10 mmt, however below YA harvest at 13.3 mmt. US WW acres in drought held steady at 53%, while spring wheat acres in drought fell 1% to 38%. Export sales at 12 mil. bu. was in line with the low expectations. YTD commitments are down 33% from YA vs. the revised USDA forecast of down 17%. Commitments represent 51% of the USDA forecast, vs. the average of 58%. The lowered export forecast at 750 mil. bu. still seems too high.
Risk Warning: Investments in Equities, Contracts for Difference (CFDs) in any instrument, Futures, Options, Derivatives and Foreign Exchange can fluctuate in value. Investors should therefore be aware that they may not realise the initial amount invested and may incur additional liabilities. These investments may be subject to above average financial risk of loss. Investors should consider their financial circumstances, investment experience and if it is appropriate to invest. If necessary, seek independent financial advice.
ADM Investor Services International Limited, registered in England No. 2547805, is authorised and regulated by the Financial Conduct Authority [FRN 148474] and is a member of the London Stock Exchange. Registered office: 3rd Floor, The Minster Building, 21 Mincing Lane, London EC3R 7AG.
A subsidiary of Archer Daniels Midland Company.
© 2021 ADM Investor Services International Limited.
Futures and options trading involve significant risk of loss and may not be suitable for everyone. Therefore, carefully consider whether such trading is suitable for you in light of your financial condition. The information and comments contained herein is provided by ADMIS and in no way should be construed to be information provided by ADM. The author of this report did not have a financial interest in any of the contracts discussed in this report at the time the report was prepared. The information provided is designed to assist in your analysis and evaluation of the futures and options markets. However, any decisions you may make to buy, sell or hold a futures or options position on such research are entirely your own and not in any way deemed to be endorsed by or attributed to ADMIS. Copyright ADM Investor Services, Inc.
