Written Commentary
CORN
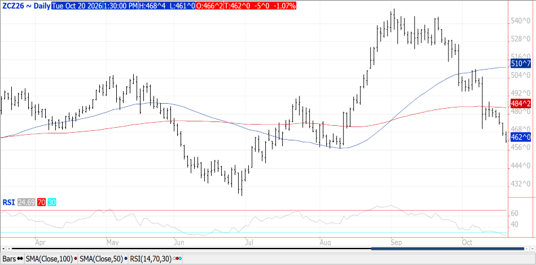
Prices were $.02-$.05 lower while spreads weaken. Dec-26 closed lower for a 6th consecutive session while falling to a fresh 2 ½ month low. Next support is at the August low at $4.57 ¼. After another session with heavy speculative selling yesterday, we’ve got the MM long position just under 195k contracts, probably closer to 180k after today. Open interest was down nearly 11k contracts. US harvest advanced 11% to 44%, below expectations of 49%. It’s the slowest pace in 7 years and below the 5-year Ave. of 52%. Delays are most pronounced in the NC Midwest with IA at 26% vs. 50% Ave., SD 29% vs. 47%, MN 38% vs. 53%, and MI 13% vs. 31%. While we continue to see flash sale announcements in soybeans, corn sales have been lacking. Until we see better demand for US corn, and/or a weather issue in SA, the path of least resistance remains lower as speculators shed length while US farmers harvest a better-than-expected crop. EU 26/27 imports as of Oct. 18th at 6.64 mt are up 40% YOY. US Gulf corn remains competitively priced with SA competition however at only $105 premium to Dalian futures, likely not pricing dynamics that would induce Chinese purchases.
SOYBEANS
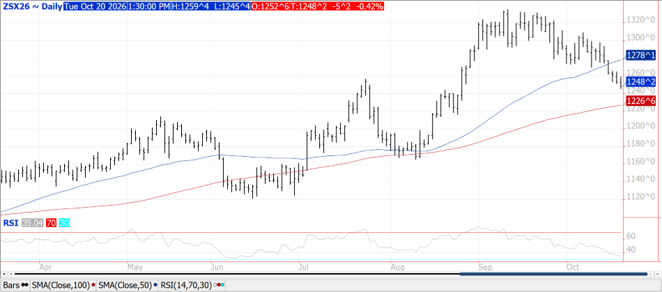
Mixed trade across the complex with beans $.04-$.05 lower, meal is down $3-$6 while oil was steady to 10 higher. Spreads weakened across the complex. Nov-26 beans fell to a 2-month low while closing lower for a 7th consecutive session. Longer term support is at the 100-day MA, currently $12.26 ¾. Dec-26 meal violated support at its 50-day MA. Dec-26 oil has support at its August low at 65.98 with MA resistance at 68.95. Crush margins were down $.07 ½ at $2.53 bu. with oil PV improving to 49%. Late yesterday Pres. Trump announced his administration will provide $8 billion in fuel assistance to US farmers to help offset record high diesel prices. Payments from the Harvest Fuel Relief program will be based on planted acres, estimated production costs and yields. Despite MM’s being light sellers across the complex yesterday, O.I. was slightly higher. Bean O.I. was up 6.4k contracts, while both meal and oil were up less than 1k. The USDA announced a flash sale of 612k mt (22.4 mil. bu.) of soybeans to China taking their purchases to roughly 17-17.5 mmt. Harvest advanced 18% to 64%, still slightly behind the 5-year Ave. of 65%. The most noted delays are in IA at 57% vs. Ave. of 74%, NE 52% vs. 71% Ave. and KS at 41% vs. 53%. Brazilian plantings at 26% were up from 15% the previous week and above the 24% pace from YA. Of China’s 11.88 mmt of soybeans imported in Sept-26, only .361 mmt were from the US, which was better zero from YA. Imports from Brazil totaled 10.7 mmt. EU soybean imports at 3.57 mmt are down 2.5% YOY. Meal imports at 5.26 mmt are up 16%.
WHEAT
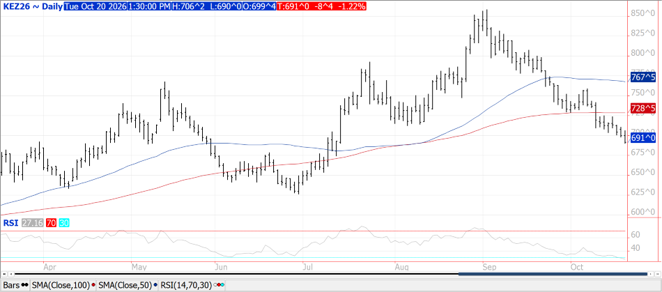
Prices range from $.08 to $.12 lower with all 3 classes closing into fresh 2–3-month lows. CGO Dec-26 was $.12 lower at $6.43 ¼, Dec-26 KC was down $.08 ½ at $6.91 while Dec-26 MIAX is off $.08 ¼ at $6.61 ¾. US winter wheat plantings advanced 12% to 63%, still below the 5-year Ave. of 69%. Emergence at 39%, also below the 5-year Ave. The EU says they are also working with Ukraine, Turkey, India and N. Africa importing countries in pushing for a safe navigation agreement for the Black Sea, upping pressure on Russia to join the discussions. Ongoing logistical issues in shipping feed grain from the Black Sea region have provided little support for prices as US wheat remains largely uncompetitive. Jordan reportedly passed on 2 offers from their 120k mt tender. EU soft wheat exports at 8.47 mmt are unchanged from YA.
Risk Warning: Investments in Equities, Contracts for Difference (CFDs) in any instrument, Futures, Options, Derivatives and Foreign Exchange can fluctuate in value. Investors should therefore be aware that they may not realise the initial amount invested and may incur additional liabilities. These investments may be subject to above average financial risk of loss. Investors should consider their financial circumstances, investment experience and if it is appropriate to invest. If necessary, seek independent financial advice.
ADM Investor Services International Limited, registered in England No. 2547805, is authorised and regulated by the Financial Conduct Authority [FRN 148474] and is a member of the London Stock Exchange. Registered office: 3rd Floor, The Minster Building, 21 Mincing Lane, London EC3R 7AG.
A subsidiary of Archer Daniels Midland Company.
© 2021 ADM Investor Services International Limited.
Futures and options trading involve significant risk of loss and may not be suitable for everyone. Therefore, carefully consider whether such trading is suitable for you in light of your financial condition. The information and comments contained herein is provided by ADMIS and in no way should be construed to be information provided by ADM. The author of this report did not have a financial interest in any of the contracts discussed in this report at the time the report was prepared. The information provided is designed to assist in your analysis and evaluation of the futures and options markets. However, any decisions you may make to buy, sell or hold a futures or options position on such research are entirely your own and not in any way deemed to be endorsed by or attributed to ADMIS. Copyright ADM Investor Services, Inc.
