Written Commentary
CORN
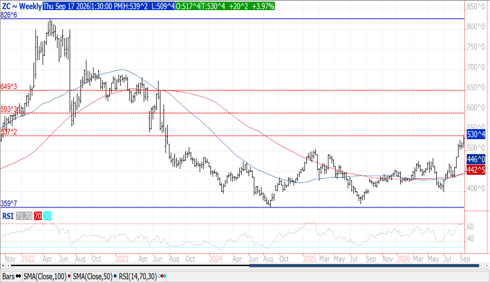
Prices were $.04-$.05 lower today while spreads firmed late. Dec-26 futures continue to hold support above LW’s low at $5.23 ¼. Corn bulls remain hopeful the Trump/Xi meeting this month will result in China’s purchase of US corn. Yesterday the Senate Ag. Committee advanced their farm bill to the full Senate floor by a vote of 12-11 that would include the year-round sale of E-15. It appears unlikely however the Senate will vote on the bill ahead of November mid-terms. France lowered their corn export forecast from the 2026 harvest to only 2.5 mmt, down 57% YOY. US exports at 40 mil. bu. were at the low end of expectations. 2026/27 commitments at 685 mil. are down 27% from YA vs. the USDA est. of down 4%. Commitments represent 21% of the USDA est. vs. the historical average of 27.5%. Mexico was the only noted buyer at 25 mil. bu. while there were cancellations of 13 mil. bu. to unknown. Friday’s COF report is expected to show feedlots held 11.279 mil. head of cattle as of Sept. 1st, up 1.8% from YA. Placements in Aug-26 are expected to be down 3.2% from YA while marketings off 3.9%. Prices remain range bound with fresh bullish news lacking.
SOYBEANS
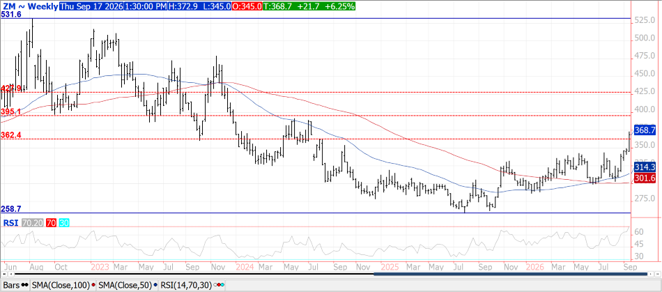
Prices are sharply mixed with meal/oil spreading dominating trade within the complex. Beans were mixed and within a penny of unchanged, meal was up $5-$8 while oil was off 50 points, rebounding well off session lows. Beans spreads weakened with several new lows while product spreads were mixed. Oct-26 meal traded to a fresh 21-month high before pulling back. Oct-26 oil rebounded after holding support at its September low at 67.77. Heavy rain continues to track across the N. Midwest, slowing crop maturation and delaying early harvest progress. Hot and dry across the S. Midwest and Delta, beneficial for harvest activities. This pattern looks to hold for another week. Chinese demand interest, slower acreage expansion in Brazil along with weather threats from a the “super El Nino” provide underlying support to the complex, while record speculative length may limit further price appreciation in the short term. The trade remains hopeful that US/China will drop reciprocal tariffs at next week’s Trump/Xi summit in Washington. Bean sales at 63 mil. were in line with expectations. YTD commitments at 758 mil. bu. are up 102% from YA vs. the USDA forecast of up 11%. Sales represent 45% of the USDA forecast, above the historical average of 36%. Chinese purchases of 875k mt take commitments to 9.86 mmt. There are another 6 mmt to unknown. Meal sales at 211k tons (187k – 26/27) were at the low end of expectations. Old crop commitments remain a record high up 15% YOY vs. the USDA forecast of up 13%. EPA data showed Aug-26 D4 RIN generation at only 693 mil., down 13% from July-26 while falling below the pace needed to reach the EPA mandates. Record US meal exports are expected to extend into 2026/27 with US share of global trade hitting a record high at 23%.
WHEAT
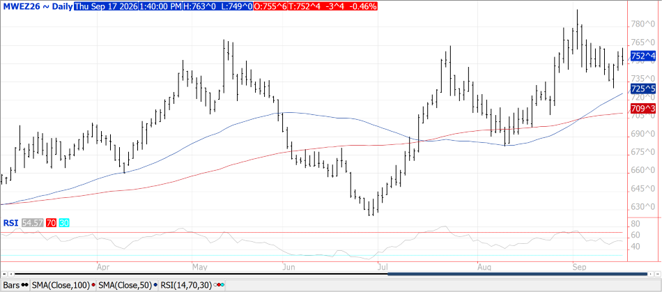
Prices ranged from $.03 to $.05 lower in choppy, 2-sided trade. CGO Dec-26 was down $.03 ¾ at $7.27, KC Dec-26 was $.05 lower at $7.94 ½ , while Dec-26 MIAX was $.03 ½ lower at $7.52 ½. Better prospects for rain in the US plains is weighed on prices. In addition, IKAR suggests Russian exports in Sept-26 may exceed 2 mmt, above their previous forecast of 1.5-2 mmt. Russian missile strikes overnight damaged cargo vessels near the port of Chornomorsk and Odesa while also damaging a bridge key to shipping grain to the Danube ports. US exports at 12 mil. bu. was in line with expectations. YTD sales are down 31% from YA vs. the USDA forecast of down 15%. Commitments represent 43% of the USDA forecast, vs. the historical average of 51%. We need to see sales pick up soon or the USDA will have no choice but to lower their export forecast. While sales to Pakistan have yet to be confirmed, wire services are reporting they have asked participants to match the lowest offers in their 750k mt tender. Those offers are between $348.80 and $353/mt CF depending on the port of entry.
Risk Warning: Investments in Equities, Contracts for Difference (CFDs) in any instrument, Futures, Options, Derivatives and Foreign Exchange can fluctuate in value. Investors should therefore be aware that they may not realise the initial amount invested and may incur additional liabilities. These investments may be subject to above average financial risk of loss. Investors should consider their financial circumstances, investment experience and if it is appropriate to invest. If necessary, seek independent financial advice.
ADM Investor Services International Limited, registered in England No. 2547805, is authorised and regulated by the Financial Conduct Authority [FRN 148474] and is a member of the London Stock Exchange. Registered office: 3rd Floor, The Minster Building, 21 Mincing Lane, London EC3R 7AG.
A subsidiary of Archer Daniels Midland Company.
© 2021 ADM Investor Services International Limited.
Futures and options trading involve significant risk of loss and may not be suitable for everyone. Therefore, carefully consider whether such trading is suitable for you in light of your financial condition. The information and comments contained herein is provided by ADMIS and in no way should be construed to be information provided by ADM. The author of this report did not have a financial interest in any of the contracts discussed in this report at the time the report was prepared. The information provided is designed to assist in your analysis and evaluation of the futures and options markets. However, any decisions you may make to buy, sell or hold a futures or options position on such research are entirely your own and not in any way deemed to be endorsed by or attributed to ADMIS. Copyright ADM Investor Services, Inc.
