Written Commentary
CORN
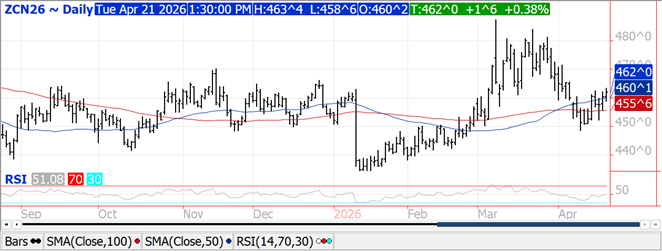
Prices surged $.10-$.15 while spreads also strengthened. Dec-26 futures surged above LW’s high, however continued to hold within the range from Fri. Sept. 11th, USDA report day. Friday’s CFTC data showed MM’s bought nearly 2k contracts of corn extending their long position to 427k contracts, just below the record high of 431k. Index funds sold just over 19K. Friday’s COF report showed US feedlots held 11.163 mil. head of cattle as of Sept. 1st, up .7% from YA, below expectations of up 1.8%. Placements in Aug-26 were down 9.2% vs. expectations of down only 3.2%. Ukraine’s corn shipments since July 1st at 1.84 mmt are actually nearly double those from YA. AgRural reports Brazil’s 2026/27 1st crop plantings have reached 27%, vs. 25% YA. US export inspections at 76 mil. bu. were above expectations and well above the 63 mil. needed each week to reach the USDA export forecast. YTD inspections at 163 mil. are up 16% from YA, vs. the USDA forecast of down 4.6%. Noted buyers were Japan – 23 mil. bu., Mexico – 21 mil. while Colombia took 10 mil.
SOYBEANS
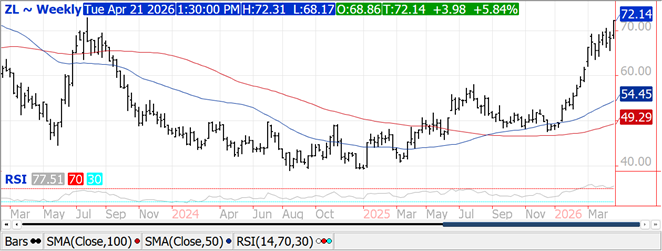
Prices were sharply higher across the complex with beans up $.20-$.25, meal was $6-$12 higher while oil was up 50-60 points. Spreads also firmed all around. Resistance for Nov-26 beans is at its contract high at $13.35 ¼. Inside trade for Oct-26 meal while oil rejected trade down to fresh 4-week lows. Weekend rains were heavy across the northern and central Midwest, slowing crop maturation and delaying harvest activities. Some late weekend rains in the S. plains, otherwise hot/dry in the S. Midwest and Delta region with widespread 100+ degree readings. Dryer across the Central Midwest and Great Lakes region this week with rains favoring the far western and eastern corn belt. Crush margins rebounded from early weakness, finishing $.04 higher at $2.40 bu. with soybean meal PV up to 51.7%. MM’s were net buyers of 26k contracts of soybean meal, extending their long positions to new record at nearly 186k. They extended their net long position across the soybean complex by nearly 14k to a new record 541k contracts. Abiove cut their Brazilian export forecast .4 mmt to 115 mmt citing China’s increased interest in US soybeans. Offsetting the lower exports, Abiove raised their crush forecast .3% to 63.5 mmt. Of the 12.14 mmt of soybean imported by China in Aug-26, only 200.5 mt were from the US, while 10.6 mmt were from Brazil. AgRural estimates Brazil’s 2026/27 plantings at 1.2% vs. just under 1% YA. China’s Sinograin is expected to auction off another 543k mt of soybeans from Govt. storage tomorrow. The trade remains hopeful that US/China will drop reciprocal tariffs this week following the Trump/Xi summit. Export inspections at 28 mil. bu. were above expectations, however, shy of the 29.5 mil. needed per week to reach the USDA export forecast. YTD inspections at 62 mil. are up 2% from YA vs. the USDA forecast of up 11%. China took just over 16 mil. bu. with the Netherlands just over 2 mil.
WHEAT
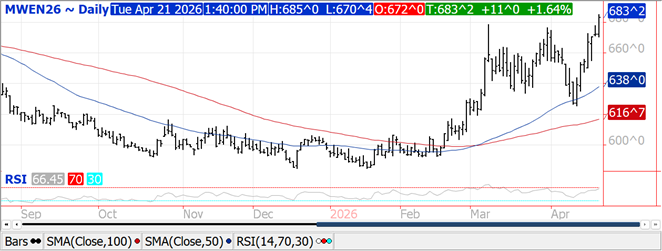
Prices ranged from $.04 to $.13 higher. CGO Dec-26 was up $.12 ½ at $7.26 ¾, KC Dec-26 was $.10 ¾ higher at $7.94 ½, while Dec-26 MIAX is $.05 higher at $7.46 ¼. MM’s were net sellers of nearly 15k contracts across the 3 classes, reducing their combined long position to 63K contracts. Russian and Ukrainian forces continue military strikes on port infrastructure and cargo vessels with no end in sight. Ukraine’s wheat shipments since July 1st at 2.33 mmt are down 44% YOY. As interior prices in both Russia and Ukraine have plunged, look for farmers in both countries to significantly cut back on winter plantings. Pakistan purchased 365k mt of wheat in last week’s 750k mt tender. The reported price was just under $349/mt CF after Pakistan asked participants to lower their offers to match the lowest one. They issued another tender for 185k mt that closes on Sept. 28th. IKAR reports Russia has been able to ship 2 mmt of wheat so far in Sept-26 as they move shipments to the Baltic Sea from the Black Sea. They also report Russia’s export price ended last week at $268/mt FOB, down $6 from the previous week. US inspections at 12 mil. bu. were in line with expectations. YTD inspections at 222 mil. bu. are down 32% from YA vs. the USDA forecast of down 15%.
Risk Warning: Investments in Equities, Contracts for Difference (CFDs) in any instrument, Futures, Options, Derivatives and Foreign Exchange can fluctuate in value. Investors should therefore be aware that they may not realise the initial amount invested and may incur additional liabilities. These investments may be subject to above average financial risk of loss. Investors should consider their financial circumstances, investment experience and if it is appropriate to invest. If necessary, seek independent financial advice.
ADM Investor Services International Limited, registered in England No. 2547805, is authorised and regulated by the Financial Conduct Authority [FRN 148474] and is a member of the London Stock Exchange. Registered office: 3rd Floor, The Minster Building, 21 Mincing Lane, London EC3R 7AG.
A subsidiary of Archer Daniels Midland Company.
© 2021 ADM Investor Services International Limited.
Futures and options trading involve significant risk of loss and may not be suitable for everyone. Therefore, carefully consider whether such trading is suitable for you in light of your financial condition. The information and comments contained herein is provided by ADMIS and in no way should be construed to be information provided by ADM. The author of this report did not have a financial interest in any of the contracts discussed in this report at the time the report was prepared. The information provided is designed to assist in your analysis and evaluation of the futures and options markets. However, any decisions you may make to buy, sell or hold a futures or options position on such research are entirely your own and not in any way deemed to be endorsed by or attributed to ADMIS. Copyright ADM Investor Services, Inc.
