Written Commentary
CORN
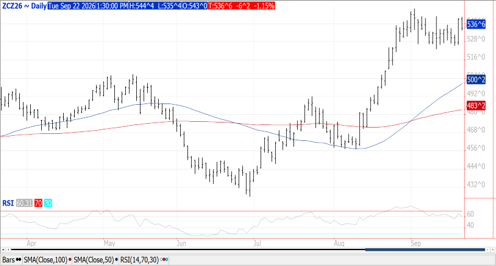
Prices were $.05-$.06 lower, drifting back toward session lows at the close. Spreads were weaker. Dec-26 continues to hold within the range from Fri. Sept. 11th, USDA report day. MM’s bought just over 30k contracts of corn yesterday extending their long position to 440k contracts, which would be a new record high. O.I however, was up less than a thousand contracts. Crop ratings held steady at 57% G/E with overall ratings holding at the season lows and just below the historical average. 92% of the crop is dented, 58% is mature, both above YA and the 5-year Ave. Harvest reached 13% vs. 10% YA and 5-year Ave. of 11%. Hot/dry conditions in the South led to good progress being made. Ratings suggest an average US yield of 178.2 bpa with production at 15.773 bil. bu. down 24 mil. from last week while just below the USDA forecast at 15.80 bil. bu. EU corn imports as of Sept. 20th at 4.47 mmt are up 27% YOY. US Gulf FOB offers have spiked vs. SA prices, perhaps an attempt to shift non-Chinese buyers to Brazil or Argentina in the event China starts loading up on US grain. If China were to purchase US corn it would be purely for political reasons as Dalian prices have fallen to only a $70 per ton premium to US Gulf prices, matching the low from 2025 and the lowest since the spring of 2022.
SOYBEANS
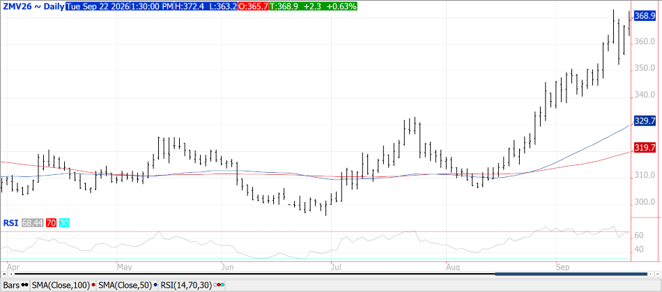
Prices finished mixed with beans down $.01-$.03, meal was up $2 while oil was off 75-95 points. Nov-26 beans continue to hover just below contract highs at $13.35 ¼. Resistance for Oct-26 meal is at $372.90 while support for Oct-26 oil is at last month’s low at 65.70. The Central Midwest is expected to get a break from the recent heavy rains with showers expected to favor the far ECB and Plain states over the next 5 days. Gradual warming this week with temperatures reaching above normal readings by the weekend. Week 2 of the outlook has above normal precipitation across the nation’s midsection. Crush margins backed up another $.03 to $2.37 bu. with meal PV rising to a 7-month high at 52.2%. Yesterday MM’s bought 13k contracts of soybeans, 8.5k meal and 3k bean oil. O.I. was up 3k in beans, while down 8.5k in meal and 7k in oil. Overnight Sinograin auctioned off just over 62% of the 543k tons of soybeans offered. China also announced plans for another auction of 514k tons next Monday. AgRural reports Brazil’s 2026/27 crop is just over 1% planted. US crop ratings held steady at 58% G/E. Composite ratings remain at cycle lows while just above the historical average. 62% of the crop is dropping leaves vs. YA and 5-year Ave. of 58%. Harvest has reached 12% vs. YA and 5-year Ave. of 8%. Updated ratings suggest an average US yield of 52.5 bpa with production at 4.511 bil. bu. down fractionally from last week while below the USDA forecast of 4.535 bil. I’d estimate Chinese purchases of US beans are approaching 14 mmt. The trade remains hopeful that US/China will drop reciprocal tariffs this week following the Trump/Xi summit. EU soybean imports at 2.67 mmt are up 14% YOY. Meal imports at 3.5 mmt are off 20.5%. US soybeans remain competitively priced against Brazilian offers. US shipments to China will start picking up this fall as Brazilian shipments start to tail off.
WHEAT
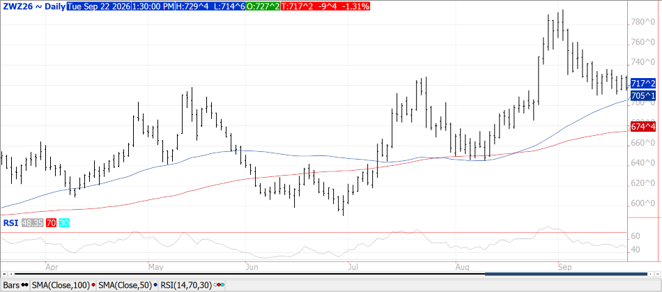
Prices ranged from $.09 to $.13 lower. CGO Dec-26 was down $.09 ½ at $7.17 ¼, KC Dec-26 was $.13 ¼ lower at $7.81 ¼, while Dec-26 MIAX was $.10 lower at $7.36 ¼. Russian and Ukrainian forces continue military strikes on port infrastructure and cargo vessels despite Russian leader Putin and Turkey’s Pres. Erdogan recent discussion for a moratorium that would allow the safe passage through the Black Sea. Russia eliminated export duties on grain shipments through the end of 2026. US spring harvest advanced to 96%, matching the YA pace and 5-year Ave. Winter wheat plantings at 17% are below the 19% pace from YA and the 5-year Ave. of 21%. 2% of the crop has emerged. Sources indicate Jordan bought 60k mt of optional origin wheat in today’s 120k mt tender. They reportedly paid $322/mt CF for Nov-26 shipment. EU soft wheat shipments at 6.3 mmt are up 2% YOY. The BAGE is forecasting Argentine 26/27 wheat production at 23.4 mmt. While down 4.4 mmt from YA, it’s still above the USDA est. of 21.5 mmt.
Risk Warning: Investments in Equities, Contracts for Difference (CFDs) in any instrument, Futures, Options, Derivatives and Foreign Exchange can fluctuate in value. Investors should therefore be aware that they may not realise the initial amount invested and may incur additional liabilities. These investments may be subject to above average financial risk of loss. Investors should consider their financial circumstances, investment experience and if it is appropriate to invest. If necessary, seek independent financial advice.
ADM Investor Services International Limited, registered in England No. 2547805, is authorised and regulated by the Financial Conduct Authority [FRN 148474] and is a member of the London Stock Exchange. Registered office: 3rd Floor, The Minster Building, 21 Mincing Lane, London EC3R 7AG.
A subsidiary of Archer Daniels Midland Company.
© 2021 ADM Investor Services International Limited.
Futures and options trading involve significant risk of loss and may not be suitable for everyone. Therefore, carefully consider whether such trading is suitable for you in light of your financial condition. The information and comments contained herein is provided by ADMIS and in no way should be construed to be information provided by ADM. The author of this report did not have a financial interest in any of the contracts discussed in this report at the time the report was prepared. The information provided is designed to assist in your analysis and evaluation of the futures and options markets. However, any decisions you may make to buy, sell or hold a futures or options position on such research are entirely your own and not in any way deemed to be endorsed by or attributed to ADMIS. Copyright ADM Investor Services, Inc.
