Written Commentary
CORN
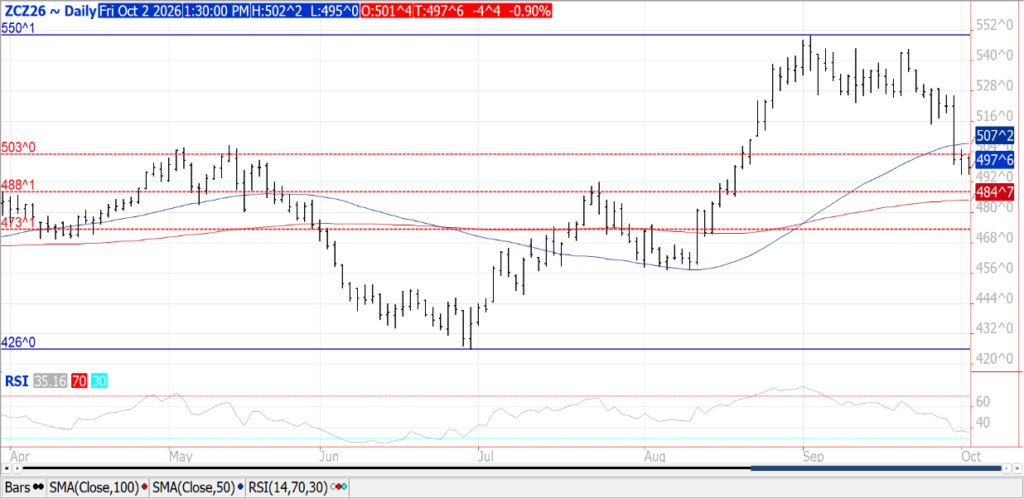
Prices finished $.04 ½ – $.05 ½ lower while spreads were steady to higher. Despite the downturn, Dec-26 futures held support (for now) at yesterday’s low. Next support is at $4.88, the midpoint between the June low and the September high. StoneX is forecasting US corn production at 16.115 bil. bu. with an average yield of 182.1 bpa. While well above the Sept-26 USDA forecast of 15.80 bil. bu., the StoneX est. is down 92 mil. bu. from their est. last month. I suspect StoneX will once again be the outlier to the upside leading up to the USDA report next Friday. Corn used for ethanol in Aug-26 at 478 mil. bu. was at the high end of expectations. I have total usage Sept-25 thru Aug-26 at 5.547 bil. bu., 3 mil. below the current USDA est. While harvest progress was slowed in the west and NC Midwest, good progress was made this week in the SE third of the corn belt, along with the N. Plains. Improving harvest conditions combined with a near record speculative length and weak exports has turned the path of least resistance to the downside. Bulls remain hopeful that Chinese demand and/or lower production from the USDA next week changes that narrative. The USDA did announce a flash sale of 218.6k tons of corn to Mexico across 3 different crop years. Someone seems to have concern over “Super” El Nino.
SOYBEANS
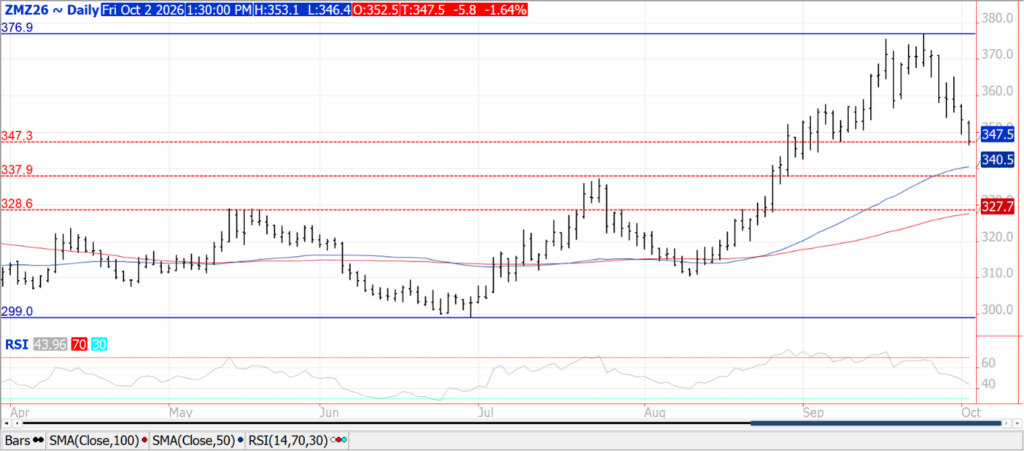
Prices were mixed with beans down $.04-$.06, meal was off $5-$7 while bean oil jumped $.01 ¼ lb. Spreads were also mixed across the complex. Nov-26 beans carved out a new 5-week low before bouncing. Dec-26 meal closed very close to its 38% retracement support at $347.30. Dec-26 oil challenged this week’s high of 69.03, drawing support from lower-than-expected stocks. Crush margins jumped $.09 ½ to $2.44 bu. with bean oil PV climbing to a 4-week high at 49.8%. StoneX is forecasting US soybean production at 4.648 bil. bu. with an average yield of 54.1 bpa, well above the Sept-26 USDA forecast of 4.535 bil. bu. and up 101 mil. bu. from their Sept-26 forecast. Like corn, I suspect the StoneX forecast will be the outlier to the high side. Census crush in Aug-26 at 210 mil. bu. was in line with expectations while bringing cumulative 2025/26 crush to 2.645 bil. bu., 10 mil. below the USDA estimate of 2.655 bil. The Ave. daily crush rate fell to a MY low at 6.77 mbd, down from 7.16 mbd in July, however above Aug-25 at 6.39 mbd. Soybean oil stocks fell to 1.696 bil. lbs., below expectations of 1.80 bil. Bean oil usage for green diesel production rose to 43.3% of the feedstocks used, the 2nd highest in 3 years. Look for the USDA to shift bean oil demand from other domestic uses into the production of biofuels. We’ll have our production estimates early next week. As harvest begins to open up across the WCB, look for some of these huge basis premiums to start crumbling, if they haven’t already.
WHEAT
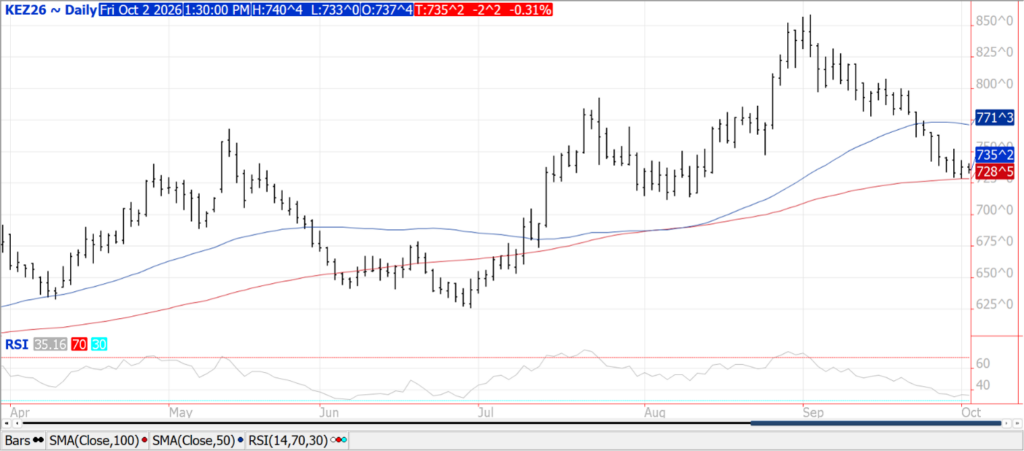
Prices closed mixed and very little changed for the day. For the week KC led declines off more than $.25, while CGO and MIAX were down $.15-$.20. Russian Pres. Putin formally rejected proposals to halt military strikes on energy refineries and vessels moving through the Black Sea while Turkey and the UN attempt to jump start new peace negotiations. Ukraine’s Ag. Minister expects his countries’ winter crop seedings, including winter wheat, will fall 15% this year. After Estonia banned the transit of Russian (and Belarusian) grain through their country to ports along the Baltic Sea, Latavia and Lithuania are considering doing the same, potentially further restricting Russia’s ability to export wheat. US winter wheat acres in drought slipped 1% to 57% while spring wheat acres in drought fell 4 % to 48%. I’d expect a much steeper drop in WW acres in drought next week. Tunisia reportedly bought 100k mt of durum with prices ranging from just over $358/mt to just under $384/mt CF depending on origin. The grain is expected to be shipped in Nov/Dec. Results from Saudi Arabia’s recent 535k mt tender likely announced over the weekend or Monday.
Risk Warning: Investments in Equities, Contracts for Difference (CFDs) in any instrument, Futures, Options, Derivatives and Foreign Exchange can fluctuate in value. Investors should therefore be aware that they may not realise the initial amount invested and may incur additional liabilities. These investments may be subject to above average financial risk of loss. Investors should consider their financial circumstances, investment experience and if it is appropriate to invest. If necessary, seek independent financial advice.
ADM Investor Services International Limited, registered in England No. 2547805, is authorised and regulated by the Financial Conduct Authority [FRN 148474] and is a member of the London Stock Exchange. Registered office: 3rd Floor, The Minster Building, 21 Mincing Lane, London EC3R 7AG.
A subsidiary of Archer Daniels Midland Company.
© 2021 ADM Investor Services International Limited.
Futures and options trading involve significant risk of loss and may not be suitable for everyone. Therefore, carefully consider whether such trading is suitable for you in light of your financial condition. The information and comments contained herein is provided by ADMIS and in no way should be construed to be information provided by ADM. The author of this report did not have a financial interest in any of the contracts discussed in this report at the time the report was prepared. The information provided is designed to assist in your analysis and evaluation of the futures and options markets. However, any decisions you may make to buy, sell or hold a futures or options position on such research are entirely your own and not in any way deemed to be endorsed by or attributed to ADMIS. Copyright ADM Investor Services, Inc.
