Written Commentary
CORN
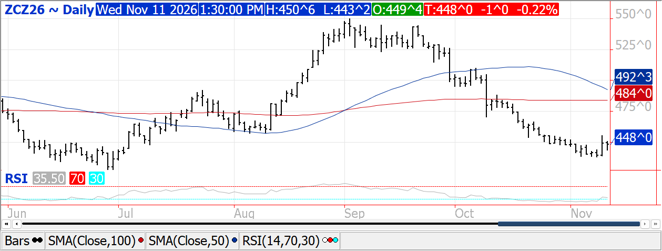
Prices ranged $.01-$.04 lower while spreads firmed. Dec-26 held within yesterday’s range. While yesterday’s USDA report may have raised the price floor and stopped the bleeding for now, to see prices push above yesterday’s high I think will likely require a more threatening forecast in South America or some unexpected demand from China. Although the USDA lowered their export forecast in yesterday’s WASDE, the current pace is still well below what is needed to reach the 3.275 bil. forecast. Higher production in Brazil continues to be absorbed by higher domestic usage. Taiwan reportedly bought 65k mt of Brazilian corn for Jan/Feb shipment at $2.20 over May-27 futures. A German Co-op lowered their corn production forecast to 4.1 mmt down 17% YOY. Yesterday the USDA lowered their EU production another .5 mmt to 47.5 mmt, down 16.5% YOY. Conab will update their Brazilian production estimate Friday. The USDA Ave. Farm price for 2026/27 MY at $4.60 bu. historically is a good fit for a stocks/use ration at 10.8%.
SOYBEANS
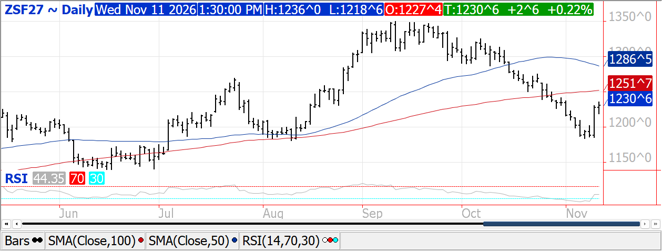
Prices were higher across the complex with beans up $.03-$.04, meal was steady to $2 higher while bean oil was up over $.01 per lb. Jan-27 beans traded above yesterday’s high with next resistance at the 100-day MA at $12.52. Dec-26 meal rejected early weakness to trade into a new high for the month. Dec-26 oil stretched out to new highs for the week supported by higher energy prices and D4 RIN values recovering back above $2. Crush margins rebounded $.14 to $1.95 bu. after falling to a 10-month low yesterday. With the USDA reports out of the way and US harvest nearing completion, the markets attention shifts to monitoring peace negotiations and South American weather, which at the moment is non-threatening. No flash sales from the USDA or EIA ethanol production data today as Govt. offices are closed in honor of Veterans Day. The USDA raised soybean oil usage for green diesel production in 25/26 MY 100 mil. lbs. to 14.9 bil. while leaving 26/27 unchanged at 17.8 bil. Yesterday’s sharply higher close suggests the market was trading production and stocks significantly higher than the pre-report estimates with a lot of 54-55 bpa yields floating around. While we’re not in a rationing situation yet, the lower US production and stocks outlook make it critical that SA achieves trendline yields. Stocks/use among global exporters remain at multi-year lows. Export sales are delayed until Friday.
WHEAT
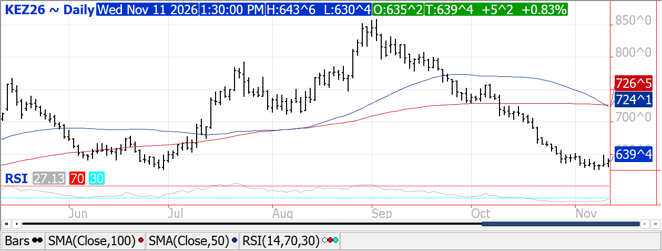
Prices firmed up late closing $.05-$.07 higher. Dec-26 CGO was up $.08 at $6.00 ¾, Dec-267 KC was $.05 higher at $6.39 ½ while Dec-26 MIAX was $.06 ½ higher at $6.35 ½. Prices were higher yesterday drawing support from strength in corn and soybeans despite the USDA data being neutral to bearish on higher-than-expected global stocks. Stocks/use among global exporters rose to 18.2%, up from 17.3% in Oct-26 while matching YA. Without progress toward peace between Ukraine/Russia or some progress on reopening the Black Sea I’d expect the market to re-inject war premium. Week 2 of the outlook brings above normal precipitation across much of the winter wheat growing areas which should further ease drought conditions as the crop heads towards dormancy. Wire services are reporting Algerian bought more than 700k mt of milling wheat around $313/mt CF. Much of the grain is believed to be sourced from Argentina with smaller volumes from the Baltic Sea area (Russia) along with Bulgaria and Romania. SovEcon lowered their Russian export forecast another .7 mmt to only 36 mmt, below the revised USDA est. of 39 mmt. They don’t see Black Sea shipping return to normal until next Spring.
Risk Warning: Investments in Equities, Contracts for Difference (CFDs) in any instrument, Futures, Options, Derivatives and Foreign Exchange can fluctuate in value. Investors should therefore be aware that they may not realise the initial amount invested and may incur additional liabilities. These investments may be subject to above average financial risk of loss. Investors should consider their financial circumstances, investment experience and if it is appropriate to invest. If necessary, seek independent financial advice.
ADM Investor Services International Limited, registered in England No. 2547805, is authorised and regulated by the Financial Conduct Authority [FRN 148474] and is a member of the London Stock Exchange. Registered office: 3rd Floor, The Minster Building, 21 Mincing Lane, London EC3R 7AG.
A subsidiary of Archer Daniels Midland Company.
© 2021 ADM Investor Services International Limited.
Futures and options trading involve significant risk of loss and may not be suitable for everyone. Therefore, carefully consider whether such trading is suitable for you in light of your financial condition. The information and comments contained herein is provided by ADMIS and in no way should be construed to be information provided by ADM. The author of this report did not have a financial interest in any of the contracts discussed in this report at the time the report was prepared. The information provided is designed to assist in your analysis and evaluation of the futures and options markets. However, any decisions you may make to buy, sell or hold a futures or options position on such research are entirely your own and not in any way deemed to be endorsed by or attributed to ADMIS. Copyright ADM Investor Services, Inc.
