Written Commentary
CORN
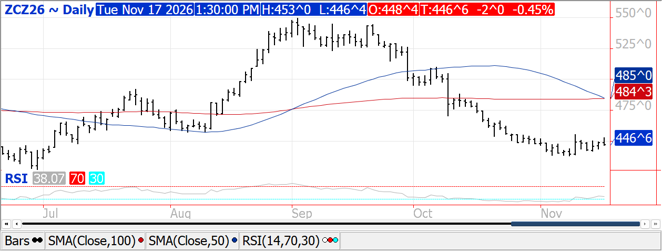
Prices were mixed while holding within $.02 of unchanged as spreads weakened. Nearby contracts continue to hold within the range set last Tuesday, USDA report day. Money managers sold another 39k contracts of corn as of last Tuesday, extending their short position to 62k contracts, their largest short in 5 months. The index fund long position in corn is down to 287k contracts, the smallest in 13 months. The index funds length across the Ag. space has fallen to its lowest level since Aug-24 as expectations for higher interest rates have weighed on future inflation expectations. US harvest progress advanced to 88%, just below the YA pace of 90% and the 5-year Ave. of 92%. The French Farm Ministry kept their countries production forecast unchanged at 7.3 mmt. Ukraine’s Ag. Ministry estimates total grain harvest so far at 50.1 mmt with 82% of the area harvested. AgRural reports Brazil’s 1st crop plantings have reached 81% as of late last week, vs. 85% YA. Tomorrow’s EIA data is expected to show last week’s ethanol production range between 322-338 mil. gallons vs. 332 mil. the previous week.
SOYBEANS
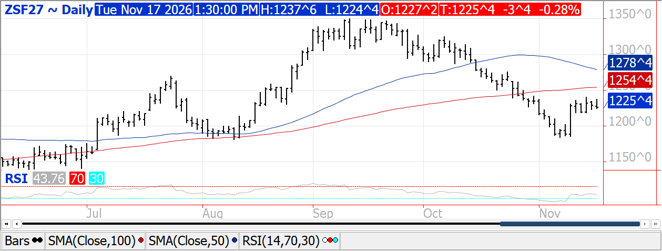
Prices were mixed with beans closing within $.03 ½ of unchanged, meal was $1-$2 higher while oil was steady to down 10 points. Bean and meal spreads weakened, while oil spreads firmed. Resistance for Jan-27 beans is the 100-day MA at $12.54 ½. Dec-26 meal surged through its 100-day MA resistance into new highs for the month. Dec-26 oil held support above this month’s low at 61.34 setting up a price rebound. Across the complex MM’s were net sellers of 101k contracts reducing their combined long position to 184k contracts, the smallest in 4 months. US harvest advanced 4% to 96% complete, vs. the 5-year Ave. of 95% and YA pace of 93%. Yesterday’s NOPA crush from October at 234.2 mil. bu. was a new all-time high and well above the Ave. estimate of 225 mil. bu. The implied census crush at 238 mil. bu. would bring the 2-month total for the 26/27 MY to 437 mil. bu. still down 1% YOY vs. the USDA forecast of up 5%. Bean oil stocks rose to 1.17 bil. lbs. above the Ave. estimate of 1.08 bil., however was within trade expectations. AgRural reports Brazil’s plantings have reached 78% as of late last week, vs. 71% YA. Markets will want assurances that China completes their purchase of 25 mmt of US soybeans for the 26/27 MY and for the next 2 MY’s. Markets will also want clarity on when or if China makes progress on the $17 bil. in non-soybean purchases and whether this will include the purchase of US corn or wheat. First step in seeing this happen will likely require the elimination of the US 10% fentanyl tariff on Chinese imports, followed by China dropping the 10% retaliatory tariffs on US Ag. goods.
WHEAT
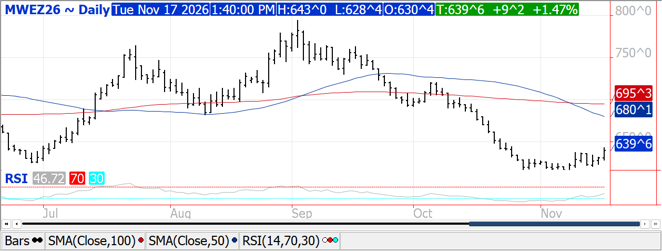
Prices ranged from $.08 to $.14 higher as markets add back war premium after Ukraine struck the Kerch Bridge that connects S. Russia with Crimea, leading to a partial collapse suggesting logistical delays from the Black Seas will extend into 2027. So far, no date has been set for the next round of tri-lateral trade talks between US, Russia and Ukraine. Dec-26 CGO was up $.08 ¼ at $5.95 ¼, Dec-26 KC was $.14 higher at $6.33 while Dec-26 MIAX was up $.09 ¼ at $6.39 ¾. MM’s sold 1k contracts combined across the 3 classes of wheat extending their short position to 106k contracts, the largest in 9 months. Winter wheat plantings advanced 3% to 92%, just below the 5-year Ave. of 94% while emergence at 82% is just above the 5-year Ave. of 81%. Ratings improved 4% to 53% G/E, vs. expectations of a 2% improvement. Ratings jumped 11% in CO, 8% in OR, 7% in TX, and 6% in KS. Ratings fell 10% in MI. Jordan passed on making any purchase in today’s 120k mt tender. Record wheat production and the need for lower imports in N. Africa and Middle East countries have mitigated the reduced supplies available from the Black Sea.
Risk Warning: Investments in Equities, Contracts for Difference (CFDs) in any instrument, Futures, Options, Derivatives and Foreign Exchange can fluctuate in value. Investors should therefore be aware that they may not realise the initial amount invested and may incur additional liabilities. These investments may be subject to above average financial risk of loss. Investors should consider their financial circumstances, investment experience and if it is appropriate to invest. If necessary, seek independent financial advice.
ADM Investor Services International Limited, registered in England No. 2547805, is authorised and regulated by the Financial Conduct Authority [FRN 148474] and is a member of the London Stock Exchange. Registered office: 3rd Floor, The Minster Building, 21 Mincing Lane, London EC3R 7AG.
A subsidiary of Archer Daniels Midland Company.
© 2021 ADM Investor Services International Limited.
Futures and options trading involve significant risk of loss and may not be suitable for everyone. Therefore, carefully consider whether such trading is suitable for you in light of your financial condition. The information and comments contained herein is provided by ADMIS and in no way should be construed to be information provided by ADM. The author of this report did not have a financial interest in any of the contracts discussed in this report at the time the report was prepared. The information provided is designed to assist in your analysis and evaluation of the futures and options markets. However, any decisions you may make to buy, sell or hold a futures or options position on such research are entirely your own and not in any way deemed to be endorsed by or attributed to ADMIS. Copyright ADM Investor Services, Inc.
