Written Commentary
CORN
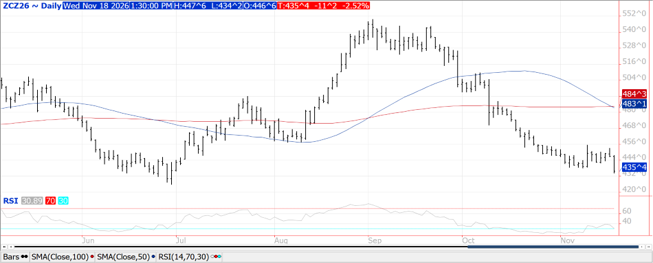
Prices were $.08-$.11 lower, closing near session lows as spreads also weakened. Dec-26 broke out of the range set last Tuesday, USDA report day. Next support is at the contract low of $4.25 ¾. Speculative traders sold 4k contracts yesterday extending their short position to 68k contracts. Open interest plunged 39k contracts, due largely to the liquidation of the Dec-26 contract. ANEC estimates Brazil will ship nearly 8.1 mmt of corn in November, if realized would be the most since Sept-23. China’s corn imports in Oct-26 at 490k mt were up 37% YOY. YTD imports at 2.6 mmt are up 101% from YA. Markets will also want clarity on whether China will make progress on the $17 bil. in non-soybean purchases annually and whether this will include the purchase of US corn or wheat. First step in seeing this happen will likely require the elimination of the US 10% fentanyl tariff on Chinese imports, followed by China dropping the 10% retaliatory tariffs on US Ag. goods. EIA data showed ethanol production slipped to 331 mil. gallons last week, down from 332 mil. the previous week, however up 3.2% YOY. Corn usage at 111 mil. bu. or 15.8 mbd,
above the 15.56 mbd needed to reach the USDA forecast of 5.650 bil. bu. If last week’s pace held over the remaining 42 weeks of the MY, corn usage would reach 5.718 bil. bu. Stocks rose to 24.9 mil. barrels, well above 22.3 mb from YA. Production margins remain firm despite a pullback in recent weeks. Tomorrow’s export sales are expected to range from 48-80 mil. bu.
SOYBEANS
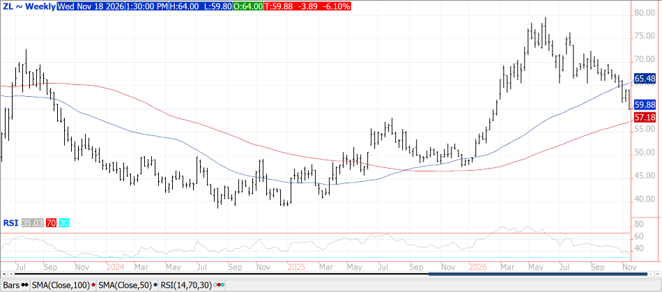
Mostly lower trade across the complex with beans down $.09-$.14, meal was steady to $1 higher while bean oil prices plunged over $.02 lbs. Bean spreads firmed while product spreads were mixed. Jan-27 beans fell to its lowest level since this last week’s USDA report. Dec-26 meal held within yesterday’s range while consolidating near its 100-day MA. Dec-26 oil collapsed below $.60 lb. for the first time in 8 months. Sharply lower trade across most of the Ag. space today as lower energy prices, strength in the US $$$ along with a non-threatening forecast in South American combined to trigger broad based commodity selling. Risk Off ! Lack of bullish headlines from APEC meeting in China also weighed on commodity valuations. President Trump briefly met and shook hands with Chinese leader Xi and Putin at the APEC gala dinner ahead of talks with both global leaders tomorrow. Crush margins plunged $.15 to $1.79 bu., the lowest in 9 months. Soymeal PV rose to a 10-month high at 52.6%. The EPA is still considering 2 proposals to reallocate an additional 770 mil. RIN’s granted SRE at the end of August. One option is to reallocate half (385 mil. RIN’s) evenly split between 2026 and 2027. The other option is to reallocate 100% in 2027. The public comment period ends Dec. 4th. Friday’s CFTC-COT update will likely show MM’s net short soybean oil for the first time since Jan-26. Markets will want assurances that China completes their purchase of 25 mmt of US soybeans for the 26/27 MY and for the next 2 MY’s. I’d estimate China’s 26/27 purchases at around 21 mmt. AgRural raised their 2026/27 Brazilian production forecast 2.4 mmt to 182.8 mmt, still below the USDA est. of 186 mmt. Tomorrow’s export sales are expected to range from 35-70 mil. bu. for beans, 200-400k tons of meal and 0-10k tons of oil.
WHEAT
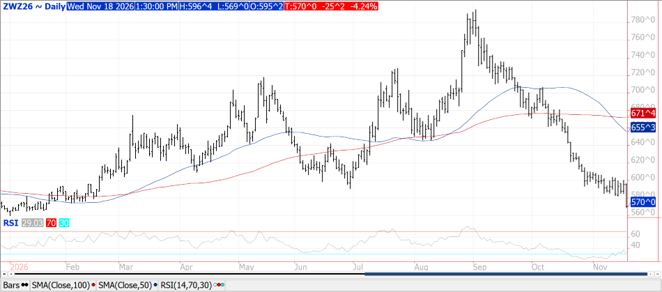
Prices ranged from $.10 to $.25 lower as markets give back all of yesterday’s higher trade. Dec-26 CGO was down $.25 ¼ at $5.70 reaching an 11-month low. Dec-26 KC was $.23 ¾ lower at $6.09 ¼ reaching a 9-month low. Dec-26 MIAX was off $.10 ½ at $6.29 ¼ while still holding within this month’s range. I guess a cordial handshake between Trump/Putin was enough to eliminate what little “War Premium” was left in the wheat market. SovEcon lowered their forecast for Russian wheat in Nov-26 to 2.7 mmt, down from 2.9 mmt in October. Ukraine’s Ag. Minister fears production in 2027 could fall by a third in 2027 to only 17 mmt due to the difficulties of war and higher input costs. With production that low, exports in 2027/28 would likely fall to only 10 mmt, the lowest in 13 years. US winter wheat acres likely increased 2-3 mil. in 2027, up from 31.2 mil. YA. Tomorrow’s export sales are expected to range from 8-15 mil. bu.
Risk Warning: Investments in Equities, Contracts for Difference (CFDs) in any instrument, Futures, Options, Derivatives and Foreign Exchange can fluctuate in value. Investors should therefore be aware that they may not realise the initial amount invested and may incur additional liabilities. These investments may be subject to above average financial risk of loss. Investors should consider their financial circumstances, investment experience and if it is appropriate to invest. If necessary, seek independent financial advice.
ADM Investor Services International Limited, registered in England No. 2547805, is authorised and regulated by the Financial Conduct Authority [FRN 148474] and is a member of the London Stock Exchange. Registered office: 3rd Floor, The Minster Building, 21 Mincing Lane, London EC3R 7AG.
A subsidiary of Archer Daniels Midland Company.
© 2021 ADM Investor Services International Limited.
Futures and options trading involve significant risk of loss and may not be suitable for everyone. Therefore, carefully consider whether such trading is suitable for you in light of your financial condition. The information and comments contained herein is provided by ADMIS and in no way should be construed to be information provided by ADM. The author of this report did not have a financial interest in any of the contracts discussed in this report at the time the report was prepared. The information provided is designed to assist in your analysis and evaluation of the futures and options markets. However, any decisions you may make to buy, sell or hold a futures or options position on such research are entirely your own and not in any way deemed to be endorsed by or attributed to ADMIS. Copyright ADM Investor Services, Inc.
