Written Commentary
CORN
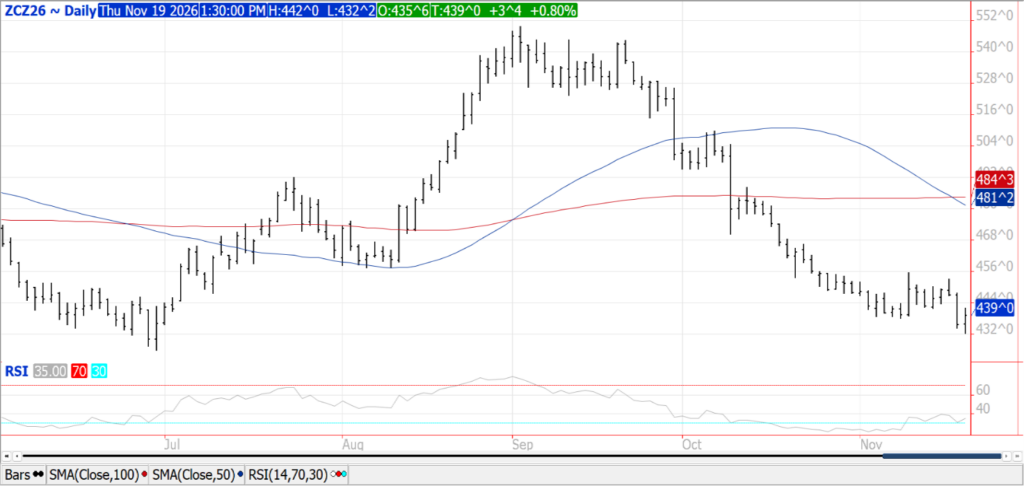
Prices were $.03-$.04 higher while spreads continued to weaken. After trading above -$.10 earlier this week, Dec/Mch is back out to -$.14, nearing the summer low of -$.16. Dec-26 traded down to a fresh 5-month low overnight before recovering. Support is at the contract low at $4.25 ¾. Speculative traders sold 24k contracts yesterday extending their short position to 92k contracts. Open interest was up 15k despite Dec-26 being down 32k. I suspect modest buying today. Prices are trying to find a level that stimulates better export demand, while SA crop prospects are on the rise. The International Grains Council lowered their global production forecast 6 mmt to 1.301 bil. mt, still above the USDA est. of 1.292 bil. mt. Total US exports at 64 mil. bu. was in line with expectations. While old crop sales at 62.5 mil. were well below 113 mil. from the previous week, they are the 2nd highest of the MY. YTD commitments at 1.152 bil., are down 28% from YA vs. the USDA forecast of down 4.5%. Commitments represent 35% of the USDA est. vs. the historical average of 44%. Leaning toward another 25-50 mil. bu. cut in the Dec-26 WASDE.
SOYBEANS
Prices were mostly lower today with beans off $.05-$.09, meal was down $2-$4 while oil recovered 20 points. Spreads weakened across the complex. Jan-27 beans have slipped to their lowest level since last Tues. USDA reports. Dec-26 meal was not able to trade back above its 100-day MA. Dec-26 oil fell to a fresh 9-month low overnight before recovering. Commodity moving headlines from the Trump, Xi, Putin summit in China were lacking. Weather in South America remains generally favorable. Addition rains in the WC region of Brazil help recharge soil moisture, while scattered rains for N. Argentina. Rainfall over the next week to favor the interior South and EC regions of Brazil. Coming into today we had MM’s still long 97k contracts of soybeans and 80k meal. The MM short in bean oil is roughly 13k. Very little change in soybean and meal O.I. while oil was up 4.4k contracts. Crush margins have rebounded $.04 at $1.84 bu. after falling to a 9-month low. While I have no reason to believe China will not finish up their 25 mmt soybean purchases for the 26/27 MY, and the next 2 MY’s, it would be nice to hear some acknowledgment post Xi, Trump, Putin meeting. No specifics yet on eliminating the remaining tariffs. Bean exports this week at 55 mil. bu. was in line with expectations. YTD commitments are up 80% from YA vs. the USDA forecast of up 13.5%. Sales represent 70% of the USDA forecast, above the historical average of 60%. Sales to China at 581k tons (55k switched from unknown) take commitments to 17.2 mmt with another 5.2 mmt to unknown. I estimate total Chinese commitments near 21 mmt. Other noted buyers were Mexico with 11 mil. and Turkey with 6 mil. bu. The USDA also announced a flash sale of 201k mt to Mexico. Meal sales at 198k tons were below expectations. YTD commitments steady with YA vs. the USDA forecast up 12%. YTD bean oil sales at 89 mil. lbs. are down 76% from YA vs. the USDA forecast of down 59%.
WHEAT
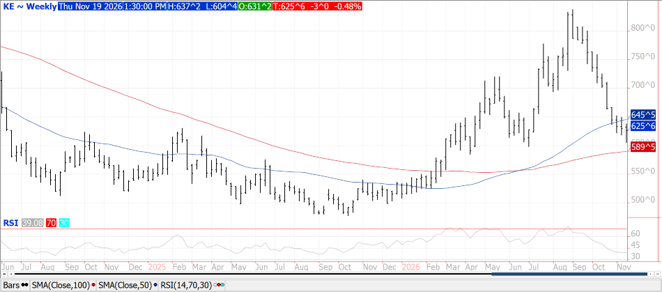
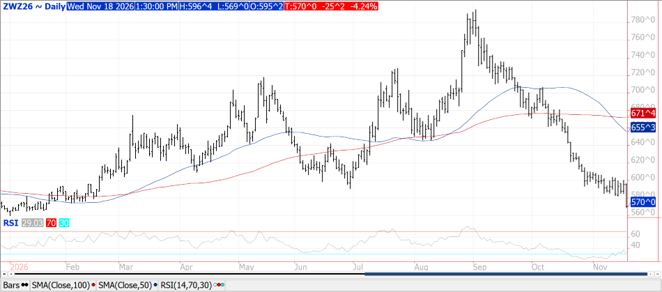
Prices ranged from $.08 to $.17 higher however, not before both CGO and KC carved out fresh multi-month lows overnight. Dec-26 CGO was up $.08 ¼ at $5.78 ¼, Dec-26 KC was $.16 ½ higher at $6.25 ¾ while Dec-26 MIAX is up $.12 ¼ at $6.41 ½. The MM short position in CGO is likely over 90k contracts, the largest in 10 months. O.I. in both CGO and KC was down 5-6k contracts. While Putin suggested Russia would retaliate for Ukraine damaging Russia’s Kercha Bridge, Russian media is reporting their Govt. is interested in bringing the war to an end. US exports at 13 mil. bu. was in line with expectations. YTD commitments are down 31% from YA vs. the USDA forecast of down 17%. US winter wheat areas in drought rose 2% in the past week to 50%. The USDA Baseline projections show all US wheat acres up 1.5 mil. in 2027 to 44 mil.
Risk Warning: Investments in Equities, Contracts for Difference (CFDs) in any instrument, Futures, Options, Derivatives and Foreign Exchange can fluctuate in value. Investors should therefore be aware that they may not realise the initial amount invested and may incur additional liabilities. These investments may be subject to above average financial risk of loss. Investors should consider their financial circumstances, investment experience and if it is appropriate to invest. If necessary, seek independent financial advice.
ADM Investor Services International Limited, registered in England No. 2547805, is authorised and regulated by the Financial Conduct Authority [FRN 148474] and is a member of the London Stock Exchange. Registered office: 3rd Floor, The Minster Building, 21 Mincing Lane, London EC3R 7AG.
A subsidiary of Archer Daniels Midland Company.
© 2021 ADM Investor Services International Limited.
Futures and options trading involve significant risk of loss and may not be suitable for everyone. Therefore, carefully consider whether such trading is suitable for you in light of your financial condition. The information and comments contained herein is provided by ADMIS and in no way should be construed to be information provided by ADM. The author of this report did not have a financial interest in any of the contracts discussed in this report at the time the report was prepared. The information provided is designed to assist in your analysis and evaluation of the futures and options markets. However, any decisions you may make to buy, sell or hold a futures or options position on such research are entirely your own and not in any way deemed to be endorsed by or attributed to ADMIS. Copyright ADM Investor Services, Inc.
