Written Commentary
It’s been a choppy week for markets, and for all the political bluster and the skirmishes between the US and Iran, little has changed; neither side is in any hurry to resume meaningful negotiations, and for all the efforts that are being made to get oil, gas and refined products as well as container traffic through the Strait of Hormuz, traffic remains limited. While the August US labour data tops the agenda, Fed’s Waller made it very clear yesterday that next Friday’s CPI data will be the key factor for the September rate decision. His position does appear to have shifted yet again to a more neutral stance than earlier in the summer, placing rather more weight on not wanting to see any renewed upward pressure, and in contrast to Warsh suggesting policy is marginally restrictive, and minded to hold rates at the September meeting barring an upside CPI surprise. There are also German Factory Orders to digest, with the UK Construction PMI and DMP survey, and Canada’s Unemployment data also ahead. The speech by BoE’s Bailey and parliamentary testimony of Bailey and other MPC members will be of more significance than that of ECB’s Lane, given the ECB has entered its communications blackout period ahead of next week’s policy meeting, while the 2-day Ambrosetti Forum gets under way in Italy, gathering together a number of key European and Italian politicians. Meanwhile, Sunday will see the Sachsen-Anhalt state election, with polls suggesting an outright majority for the far-right AfD, though the greater immediate concern are the run of attempted sabotage attacks this week on the power grid, which some commentators suggest is a consequence of Germany attributing responsibility for a failed, explosive-laden drone attack at Leipzig/Halle Airport to Russian state-sponsored hybrid warfare. On a separate note regarding energy markets, yesterday saw an unusual divergence between Brent Crude and ICE Gasoil, with the latter seeing a sharp drop of >1.0%, despite a rise in Brent, and the divergence continues today with Brent down 0.2% and GasOil down a further 2.0%, and notably no signs that the much discussed pressures on refined product (diesel, jet fuel, etc) supply chains is shifting significantly. Speculative positioning in energy futures has seen a sharp rise in net longs in refined products, so this may be mostly position unwinding, and possibly related to yesterday’s GasOil options expiry.
** Japan **
While the overnight Household Spending data was much weaker than expected, the series is volatile, with many expecting a sharp rebound in August, and unlikely to deter the BoJ from a further rate hike. Rather more notable this week has been a clear shift in the fortunes of the JPY and long-term JGB yields, as well as a market re-pricing of the BoJ’s rate trajectory. Markets are always primarily a function of flows and momentum, and as much as Japanese and US political policymakers may want to claim that their rhetoric and recent FX intervention was the driver, it is more likely that Ueda’s hawkish shift, Takata putting an outsized rate hike on the table (he is an outlier, and this is highly unlikely to happen, but the signal is aggressive) that is driving the change in flows. Notably, Japan investors are increasingly net sellers of foreign assets according to weekly flow data, and there appears to be a considerable unwind of JPY-funded carry trades, at least if the reversal in CHF/JPY cross rate is anything to go by (see attached chart).
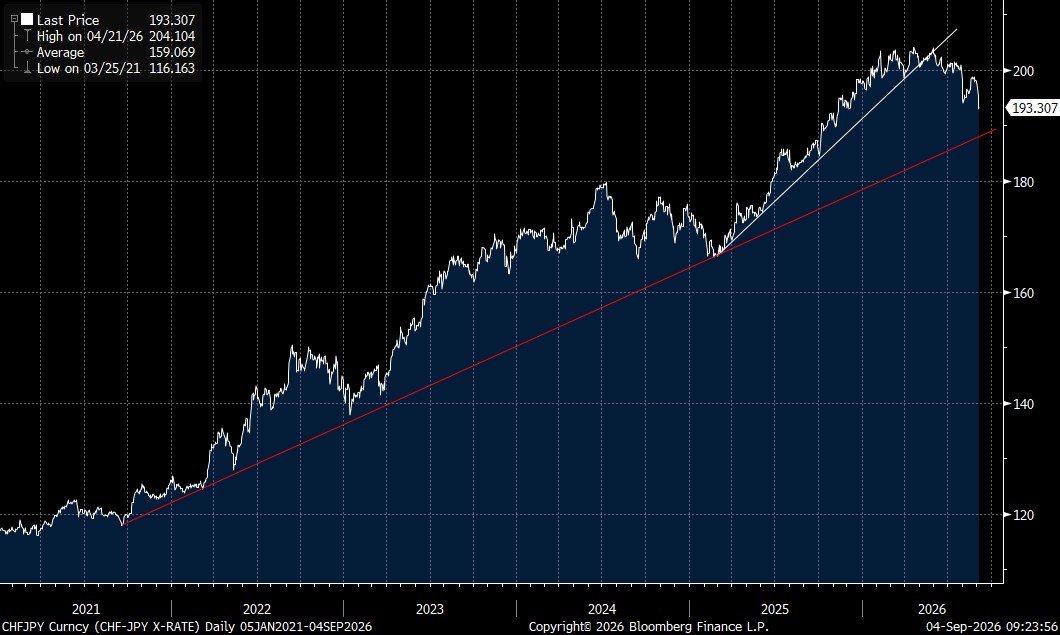
While unsurprising from the aspect of the BoJ finally tacitly conceding that it is behind the curve, the risk is that with the JPY clearly very undervalued on any Purchasing Power Parity (PPP) metric, the move lower in USD/JPY may prove to be much sharper than many are anticipating. As Finance Minister Katayama has previously opined before she took office, fair value for the JPY may be rather closer to a 120-130 range. While that may seem a very big stretch of the imagination, if momentum gathers pace, then the risk of a messy unwind of carry trades allied with Japanese repatriation flows should not be ignored.
** U.S.A. – August labour data **
Warsh’s speech was notable for placing much more emphasis on the Unemployment Rate, seen steady at 4.1%, and the low level of weekly jobless claims (little changed at 206K), playing down Average Hourly Earnings and wages generally in terms of a key inflation outlook factor, and essentially omitting Payrolls, which are expected to rebound from the surprise -23K headline drop in July to +55K, as ever subject to revisions. Markets are however, creatures of habit, and it will probably take quite a long time to condition a shift in emphasis from the establishment survey Payrolls data to the household survey that provides the Unemployment Rate, meaning that initial market reaction will probably remain sensitive to Payrolls outliers and revisions, even if this does prove short-lived, i.e. gives way to more in-depth analysis of the Household survey data.
