Written Commentary
CORN
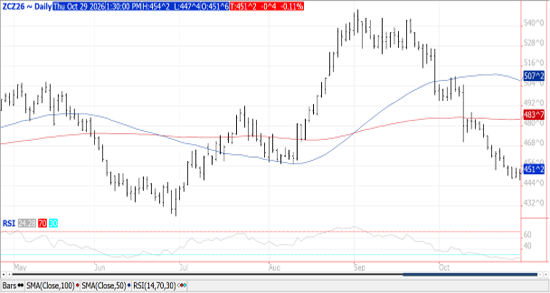
Prices were mixed and little changed while spreads weakened. Dec-26 fell to a fresh 4-month low before recovering. Overall prices continue to consolidate around $4.50. Speculative traders were net buyers of 3k contracts yesterday, while open interest surged 29k contracts. Yesterday’s EIA data showed ethanol production rose to 329 mil. gallons last week, up from 322 mil. the previous week while up 2.5% YOY. Production was above the pace needed to reach the USDA corn usage forecast for the first time in 6 weeks. Production margins are strong as energy prices remain high while corn and natural gas prices have slid. Export sales at 51 mil. bu. were in line with expectations. YTD commitments are down 34% from YA vs. the USDA forecast of down 4%. Commitments represent 28% of the USDA forecast vs. the historical average of 38%. Noted buyers were unknown – 16 mil., Mexico – 12.5 mil. while 10 mil. bu. were sold to Japan. Bulls are hopeful corn will also be on China’s wish list. While US Gulf prices have recovered to roughly $115 per ton over Dalian futures, they are still well shy of the $150 premium they are typically at for China to show interest.
SOYBEANS
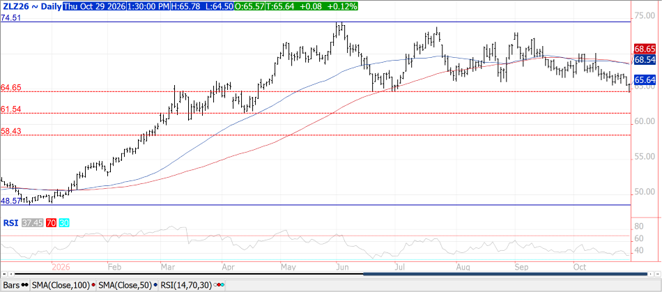
Prices turned mixed with beans closing steady to $.05 lower, meal was down $2-$5 while oil was steady to 10 points higher. Nov-26 beans fell to a fresh 2-month low before recovering. Dec-26 meal also fell to a 2-month low while slicing through its 100-day MA support. Dec-26 oil for now rejected trade below its June-26 low at 64.62 and its 38% Fibonacci retracement support. We had MM’s still net long 450k contracts combined across the complex at yesterday’s close. While still historically large, it is off from the recent record of 558k. Soybean O.I. was down 26k contracts, meal was off 7.7k while oil was up 11.5k. Crush margins were down another $.08 at $2.27 bu. Sinograin is expected to auction off another 400k mt of soybeans next Tues. Nov. 3rd. Their last auction sold only 172k mt, roughly a third of the total volume offered. Bean exports at 95 mil. were at the high end of expectations. YTD commitments are up 80% YOY vs. the USDA forecast of up 12%. Sales represent 62% of the USDA forecast, above the historical average of 52%. Sales to China at 1.627 mmt take commitments to 15.07 mmt with another 5.8 mmt to unknown. Other noted buyers were Spain – 8 mil. while Pakistan and Vietnam purchased 4-5 mil. bu. each. Meal sales at 348k tons were in line with expectations. YTD commitments are down 4% from YA vs. the USDA forecast of up 11%. YTD bean oil sales at 80 mil. lbs. are down 77.5% from YA vs. the USDA forecast of down 59%.
WHEAT
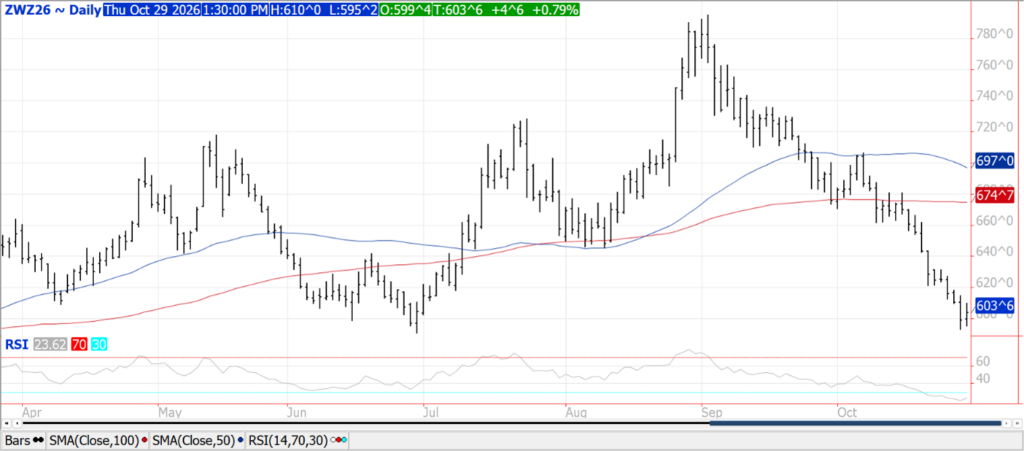
Prices snapped back closing $.02-$.05 higher following reports China sought offers for US SRW wheat. While no sales have been confirmed it does reopen to possibility China will begin to fulfill their commitment to purchase $17 bil. annually ($10.5 bil. prorated for 2026) in US agricultural goods. CGO Dec-26 was $.04 ¾ higher at $6.03 ¾, Dec-26 KC was $.02 ¼ higher at $6.45 ¼ while Dec-26 MIAX was $.04 ¾ higher at $6.24 ½. CGO and KC both fell to 3-4 month lows recently while MIAX set new contract lows. Wire services report that at least 1 vessel has already passed safely through the Kerch Strait into the Black Sea. Time will tell whether a recent cease-fire agreement in the Kherson region will hold (or expand) or whether vessels can safely navigate through the Black Sea. Prospects for peace and the reopening of the Black Sea have pressured prices the past 2 months. Export sales at 31 mil. bu. was a MY high and above expectations. YTD commitments are still down 29% YOY vs. the USDA forecast of down 17%. Commitments represent 56% of the USDA forecast, vs. the historical average of 61%. Noted buyers were Philippines – 8 mil. while Indonesia and Korea bought 5-6 mil. each. US winter wheat area in drought rose 1% this week to 50%.
Risk Warning: Investments in Equities, Contracts for Difference (CFDs) in any instrument, Futures, Options, Derivatives and Foreign Exchange can fluctuate in value. Investors should therefore be aware that they may not realise the initial amount invested and may incur additional liabilities. These investments may be subject to above average financial risk of loss. Investors should consider their financial circumstances, investment experience and if it is appropriate to invest. If necessary, seek independent financial advice.
ADM Investor Services International Limited, registered in England No. 2547805, is authorised and regulated by the Financial Conduct Authority [FRN 148474] and is a member of the London Stock Exchange. Registered office: 3rd Floor, The Minster Building, 21 Mincing Lane, London EC3R 7AG.
A subsidiary of Archer Daniels Midland Company.
© 2021 ADM Investor Services International Limited.
Futures and options trading involve significant risk of loss and may not be suitable for everyone. Therefore, carefully consider whether such trading is suitable for you in light of your financial condition. The information and comments contained herein is provided by ADMIS and in no way should be construed to be information provided by ADM. The author of this report did not have a financial interest in any of the contracts discussed in this report at the time the report was prepared. The information provided is designed to assist in your analysis and evaluation of the futures and options markets. However, any decisions you may make to buy, sell or hold a futures or options position on such research are entirely your own and not in any way deemed to be endorsed by or attributed to ADMIS. Copyright ADM Investor Services, Inc.
