Written Commentary
CORN
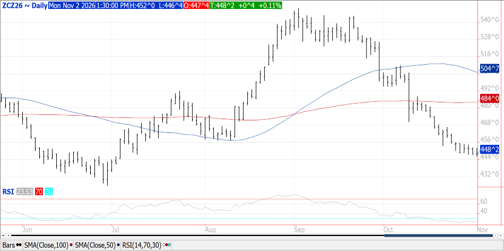
Prices were $.01-$.02 higher in 2-sided trade. Spreads weakened ahead of the Goldman roll period for the Dec-26 contract that begins on Friday. Dec-26 traded to a fresh 4-month low before rebounding. Friday’s CFTC report showed Money managers sold just over 90k contracts cutting their long position to only 56k contracts, the smallest in 4 months. Index funds have also been net sellers for 7 of the past 8 weeks. The European Commission lowered EU corn production another 1.3 mmt to 47 mmt however held their import forecast unchanged at 25 mmt. AgRural reports Brazil’s first crop plantings have reached 63% vs. 59% YA. I look for US harvest to reach 74% as of yesterday. Bulls remain hopeful US corn will be on China’s wish list however the path of least resistance remains lower until US demand improves and/or a more threatening SA forecast. Export inspections at 35 mil. bu. was in line with expectations while well below the 66 mil. needed to reach the USDA export forecast. YTD inspections are down 13% YOY, vs. the USDA forecast of down 4%. Mexico was the only noted buyer with 20.5 mil. bu. In addition, the USDA announced flash sales this AM of 1.730k mt (68 mil. bu.) of corn to Mexico, with 45 mil. bu. for 26/27 MY and 23 mil. for 27/28. There was 438 mil. bu. of corn used to produce ethanol in Sept-26, at the low end of expectations. To reach the current USDA usage forecast for 26/27 MY of 5.650 bil. bu., usage will need to average 474 mil. bu. per month.
SOYBEANS
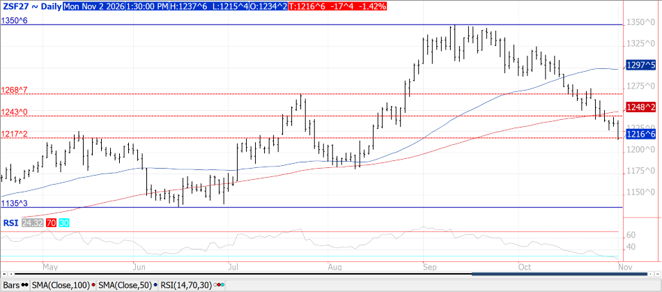
Lower trade across the complex driven by speculative selling and a favorable weather outlook in South America. Beans were $.13-$.18 lower, meal was off $5 while oil was down 80-90 points. Bean spreads weakened while product spreads firmed. Jan-27 beans fell to a 2 ½ month low while closing below its 68% Fibonacci retracement. Dec-26 meal fell to a fresh 2-month low while oil held above LW’s low. Across the soybean complex MM’s were net sellers of 70k contracts, reducing their combined long position to 411.5k contracts, while the lowest in 2 months, it remains historically large. I estimate Chinese purchases at roughly 19 mmt. Sinograin is expected to auction off another 400k mt of soybeans tomorrow. Their last auction they sold only 172k mt, roughly a third of the total volume offered. Soybean plantings in Mato Grosso, Brazil’s largest producing state, have reached 89% as of Friday, above the 76% pace YA and the 5-year Ave. of 78.5%. AgRural reports plantings in Brazil have reached 53% vs. 47% YA. I look for US harvest to have reached 90%. Soybean inspections at 90 mil. bu. was in line with expectations. YTD inspections are up 56% from YA vs. the USDA forecast of up 12%. China took 56 mil. bu. while Mexico, Italy, and Egypt all took 4 – 5 mil. The USDA also reported a flash sale of 136k mt (5 mil. bu.) to China. Sept-26 crush at 199 mil. bu. was slightly below expectations. To reach the USDA forecast of 2.780 bil. bu. crush will need to average 235 mil. bu. per month, October through August. Bean oil stocks at 1.458 bil. lbs. were below expectations.
WHEAT
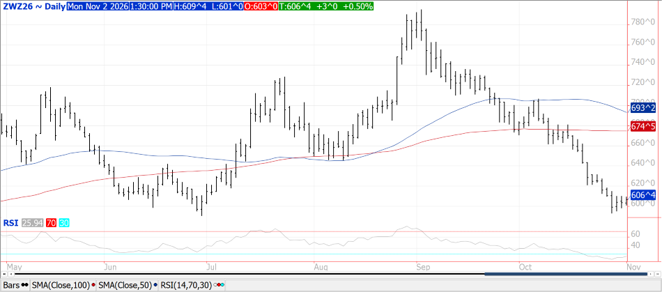
Prices closed with modest gains in 2-sided trade. CGO Dec-26 was $.03 higher at $6.06 ½, Dec-26 KC was up $.01 ¾ at $6.46 while Dec-26 MIAX was up $.02 at $6.25 ¾. MM’s were net sellers of 40k contracts combined across the 3 classes extending their short position to 80.5k contracts, the largest in 8 months. The MM short position in CGO has swelled to 75k contracts, the largest in 5 months. Prices will be sensitive to any hint of Chinese interest. IKAR reports the export price for Russian wheat at Baltic Sea ports ended last week at $260/mt, down $4 from the previous week. They raised their Oct-26 export forecast to just above 3 mmt, while suggesting Nov-26 could be slightly higher. The European Commission lowered their EU production forecast another .5 mmt to 123.7 mmt. No firm date set for tri-lateral peace talks between US, Russia and Ukraine while the fighting continues. Export inspections at only 3 mil. bu. were below expectations and the lowest in years. YTD inspections are down 36% from YA vs. the USDA forecast of down 17%. I look for US WW plantings to have reached 85% with crop rating starting at 45% G/E.
Risk Warning: Investments in Equities, Contracts for Difference (CFDs) in any instrument, Futures, Options, Derivatives and Foreign Exchange can fluctuate in value. Investors should therefore be aware that they may not realise the initial amount invested and may incur additional liabilities. These investments may be subject to above average financial risk of loss. Investors should consider their financial circumstances, investment experience and if it is appropriate to invest. If necessary, seek independent financial advice.
ADM Investor Services International Limited, registered in England No. 2547805, is authorised and regulated by the Financial Conduct Authority [FRN 148474] and is a member of the London Stock Exchange. Registered office: 3rd Floor, The Minster Building, 21 Mincing Lane, London EC3R 7AG.
A subsidiary of Archer Daniels Midland Company.
© 2021 ADM Investor Services International Limited.
Futures and options trading involve significant risk of loss and may not be suitable for everyone. Therefore, carefully consider whether such trading is suitable for you in light of your financial condition. The information and comments contained herein is provided by ADMIS and in no way should be construed to be information provided by ADM. The author of this report did not have a financial interest in any of the contracts discussed in this report at the time the report was prepared. The information provided is designed to assist in your analysis and evaluation of the futures and options markets. However, any decisions you may make to buy, sell or hold a futures or options position on such research are entirely your own and not in any way deemed to be endorsed by or attributed to ADMIS. Copyright ADM Investor Services, Inc.
