Written Commentary
CORN
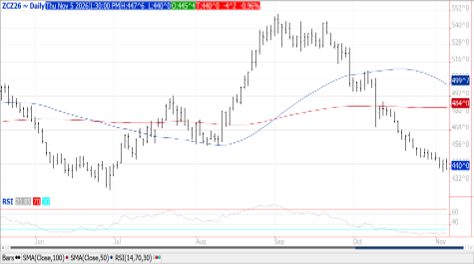
Prices were $.02-$.04 lower, closing at session lows. Spreads weaken ahead of day 1 of the Goldman roll tomorrow for the Dec-26 contracts. Speculative traders bought 12.5k contracts yesterday, extending their long position to 63k. They likely sold that much, or more, today. The Ave. production est. in the Reuters poll at 15.961 bil. bu. is down 73 mil. bu. from the USDA forecast from Oct-26. Ending stocks are expected to fall only 9 mil. bu. to 1.840 bil. Weekly exports at 51 mil. bu. was in line with expectations. YTD commitments are down 34% YOY vs. the USDA down 4%. Commitments represent 30% of the USDA est. vs. the historical average of 40%. Prices are trying to carve out a seasonal low, big sales to Mexico this week should help, lack of a threatening forecast in SA isn’t. China’s Commerce Minister suggested additional purchases of US Ag. goods hinges on both sides implementing a $60 bil. reciprocal tariff-cut agreement. The 2 sides are expected to meet to discuss tariff cuts before the end of the year.
SOYBEANS
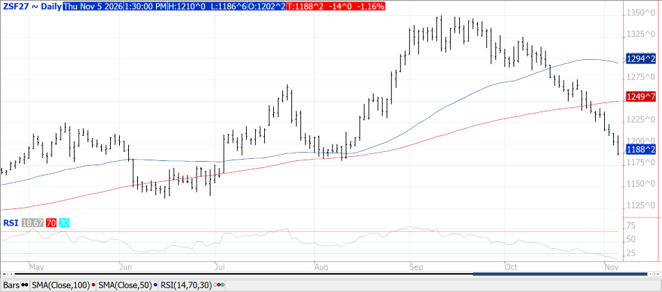
Prices were mostly lower with beans down $.10-$.14, meal is mixed while oil was off another $.01+ per lbs. Bean and meal spreads weakened while oil spreads were mixed. Jan-27 beans have closed lower 9 consecutive sessions with next support is at the Aug-26 low at $11.80 ¾. Dec-26 oil has fallen to a fresh 7-month low with next support at a 50% retracement just above 61.50. Yesterday’s net selling across the complex took the combined MM long position down to 360k, still historically large however below the recent record of 558k. Likely well under 350k after today’s trade. The positive gridlock vibes from the mid-term elections lasted 1 day as US equity markets have plunged. Fears that a Democratic Congress will lead to more regulation and a slowdown in AI buildout across the country has weighed heavily on technology shares. The DJIA and SP 500 are currently off 3.3% and 4.1% respectively, while the Nasdaq is off 5.2%. The Ave. production est. in the Reuters poll at 4.597 bil. bu. is up 35 mil. bu. from the USDA forecast in Oct-26. Ending stocks are expected to rise 16 mil. bu. to 331 mil. Soybean exports at 54 mil. was in line with expectations. YTD commitments are up 76% from YA vs. the USDA forecast of up 12%. Sales represent 66% of the USDA forecast, above the historical average of 55%. Sales to China at 894k tons (442k switched from unknown) take commitments to 15.95 mmt with another 5.6 mmt to unknown. Meal sales were in line with expectations while YTD commitments are down 2% YOY vs. the USDA forecast of up 11%. YTD bean oil sales at 84 mil. lbs. are down 77% from YA vs. the USDA forecast of down 59%.
WHEAT
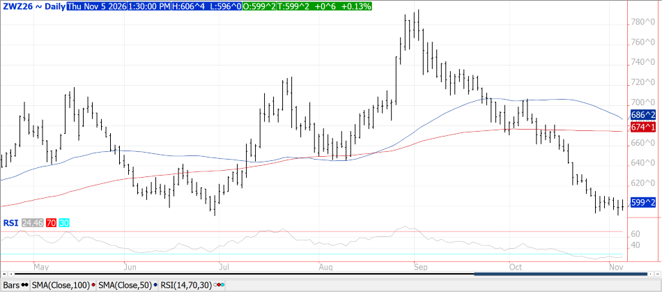
Prices ranged from steady to $.05 higher in 2-sided trade. CGO Dec-26 was up $.00 ¾ at $5.99 ¾, Dec-26 KC was $.03 higher at $6.35 ¾, while Dec-26 MIAX is up $.03 ¼ at $6.20. Prices will remain sensitive to Chinese demand interest, or lack thereof. Ukraine’s grain shipments in Oct-26 rose 26% to nearly 1.1 mmt. Roughly 20% was moved through Danube River ports with the balance through Western land borders. Markets nervously await tri-lateral peace talks between US, Russia and Ukraine in the UAE on Nov. 10th and 11th. Export sales at 20 mil. bu. was in line with expectations. YTD commitments are down 28% YOY vs. the USDA forecast of down 17%.
Risk Warning: Investments in Equities, Contracts for Difference (CFDs) in any instrument, Futures, Options, Derivatives and Foreign Exchange can fluctuate in value. Investors should therefore be aware that they may not realise the initial amount invested and may incur additional liabilities. These investments may be subject to above average financial risk of loss. Investors should consider their financial circumstances, investment experience and if it is appropriate to invest. If necessary, seek independent financial advice.
ADM Investor Services International Limited, registered in England No. 2547805, is authorised and regulated by the Financial Conduct Authority [FRN 148474] and is a member of the London Stock Exchange. Registered office: 3rd Floor, The Minster Building, 21 Mincing Lane, London EC3R 7AG.
A subsidiary of Archer Daniels Midland Company.
© 2021 ADM Investor Services International Limited.
Futures and options trading involve significant risk of loss and may not be suitable for everyone. Therefore, carefully consider whether such trading is suitable for you in light of your financial condition. The information and comments contained herein is provided by ADMIS and in no way should be construed to be information provided by ADM. The author of this report did not have a financial interest in any of the contracts discussed in this report at the time the report was prepared. The information provided is designed to assist in your analysis and evaluation of the futures and options markets. However, any decisions you may make to buy, sell or hold a futures or options position on such research are entirely your own and not in any way deemed to be endorsed by or attributed to ADMIS. Copyright ADM Investor Services, Inc.
