Written Commentary
CORN
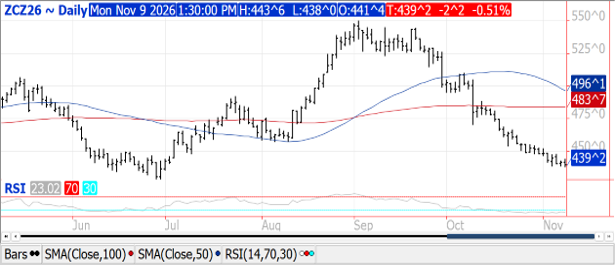
Prices were $.03-$.04 lower closing near session lows. Dec-26 carved out a fresh 4-month low with next support at the contract low of $4.25 ¾. Spreads firmed a touch. Friday’s CFTC data showed money managers sold nearly 79k contracts, flipping their position around to net short for the 1st time in 4 months. The index fund long position is down to 288k contracts, a 53-week low. For tomorrow’s USDA reports I’ve got production at 16.055 bil. with an average yield of 181.4 bpa. Since 1990 this year’s pattern of lower yields in August and Sept. followed by higher yields in October has happened only 5 times. In all 5 years the USDA went on to raise yields again in November. I’ve got stocks growing to 1.870 bil. AgRural reports Brazil’s 1st crop plantings have reached 71%. As of Nov. 1st, EU corn imports at 7.4 mmt are up 34.5% YOY. Ukraine’s Ag. Ministry reports exports since July 1st at nearly 2.3 mmt are slightly above that of a YA. I look for US harvest to have advanced to nearly 90%. Export inspections at 36 mil. bu. was in line with expectations while well below the 67 mil. needed to reach the USDA export forecast. YTD inspections are down 16% from YA, vs. the USDA forecast of down 4%. Mexico was the most noted buyer with 14 mil. bu. while the USDA also announced a flash sale of 110k mt (4.3 mil. bu.) to Mexico.
SOYBEANS
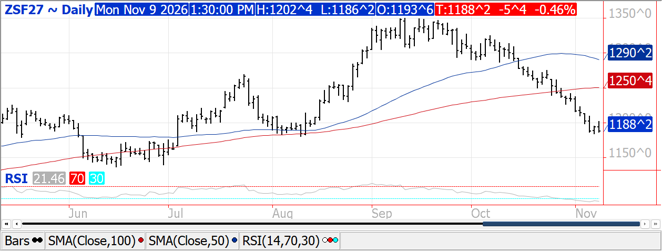
Prices were mixed and little changed across the complex today. Beans were $.03-$.05 lower, meal was steady to $1.50 higher while bean oil was down 15-25 points. On Friday Jan-27 soybeans ending a streak of 9 consecutive lower closes. Support for Jan-27 beans is at $11.80 ¾. Markets await USDA production and WASDE updates tomorrow while tri-lateral peace talks between US, Russia and Ukraine are scheduled for Tuesday and Wednesday in the UAE. South American weather forecasts remain non-threatening. Moderate to heavy precipitation is expected across Central and Northern growing areas of Brazil over the next 2 weeks, beneficial for yield prospects. Friday’s CFTC data showed money managers were net sellers of 127k contracts across the soybean complex, reducing their combined long position to 285k contracts, the smallest in 2 months and well below the recent record of 558k. The index fund long position in soybeans fell to a 19-month low at 130k contracts. Crush margins (Jan/Jan) rebounded $.04 to $2.00 bu. with bean oil PV slipping to 49.2%. I’ve got US production at 4.592 bil., with stocks at 335 mil. I’d estimate Chinese purchases at 19.5-20 mmt. I look for the USDA to raise exports another 10 mil. bu. AgRural reports Brazil’s plantings have reached 64% as of last Thursday, just above the YA pace of 61%. EU soybean imports as of Nov. 1st at 4.06 mmt are down 3.6% YOY. Meal imports at 6.14 mmt are down 15%. US bean harvest is likely approaching 95%. Soybean inspections at 70 mil. bu. was in line with expectations. Last week’s inspections were revised up by nearly 2.5 mil. bringing YTD inspections to 58% above YA vs. the USDA forecast of up 12%. China took 47 mil. bu. while Mexico and Bangladesh took 6-7 mil. each.
WHEAT
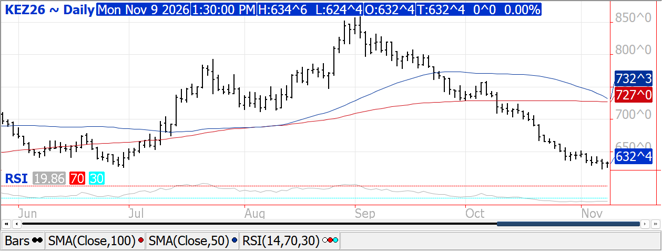
Prices ranged from $.03 lower to $.06 higher in choppy 2-sided trade. CGO Dec-26 was $.03 lower at $5.88, Dec-26 KC was steady at $6.32 ½, while Dec-26 MIAX was $.06 higher at $6.22. CGO and KC are both holding within Friday’s range. MM’s sold 25k contracts combined across the 3 classes, extending their short position to 105k contracts, the largest in 9 months. At Friday’s close we have the MM short position in CGO up to 93k contracts, the largest in 10 months. I’ve got US wheat ending stocks holding steady at 740 mil. bu. After cutting exports 25 mil. bu. last month, I see the USDA holding steady at 750 mil. The recent price plunge has left US wheat much more competitive in the global marketplace. APK Inform raised their Ukrainian production forecast 1 mmt to 26.5 mmt, while also raising their export forecast 1 mmt. Ukraine’s Ag. Ministry reports exports since July 1st have only reached 4 mmt, down 39% YOY. EU soft wheat exports thru Nov. 1st at 9.7 mmt are up 2.6% YOY. IKAR reports Russian export wheat prices from Baltic ports ended last week at $257/mt FOB, down $4 from the previous week. Export inspections at 9 mil. bu. was in line with expectations. YTD inspections are down 36% from YA vs. the USDA forecast of down 17%.
Risk Warning: Investments in Equities, Contracts for Difference (CFDs) in any instrument, Futures, Options, Derivatives and Foreign Exchange can fluctuate in value. Investors should therefore be aware that they may not realise the initial amount invested and may incur additional liabilities. These investments may be subject to above average financial risk of loss. Investors should consider their financial circumstances, investment experience and if it is appropriate to invest. If necessary, seek independent financial advice.
ADM Investor Services International Limited, registered in England No. 2547805, is authorised and regulated by the Financial Conduct Authority [FRN 148474] and is a member of the London Stock Exchange. Registered office: 3rd Floor, The Minster Building, 21 Mincing Lane, London EC3R 7AG.
A subsidiary of Archer Daniels Midland Company.
© 2021 ADM Investor Services International Limited.
Futures and options trading involve significant risk of loss and may not be suitable for everyone. Therefore, carefully consider whether such trading is suitable for you in light of your financial condition. The information and comments contained herein is provided by ADMIS and in no way should be construed to be information provided by ADM. The author of this report did not have a financial interest in any of the contracts discussed in this report at the time the report was prepared. The information provided is designed to assist in your analysis and evaluation of the futures and options markets. However, any decisions you may make to buy, sell or hold a futures or options position on such research are entirely your own and not in any way deemed to be endorsed by or attributed to ADMIS. Copyright ADM Investor Services, Inc.
