Written Commentary
CORN
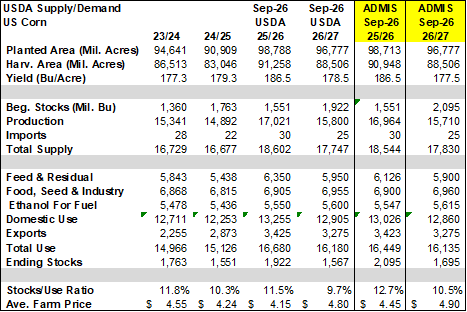
Prices surged in the 2nd half of the session closing $.07-$.11 higher while spreads were steady to firm. Dec-26 ran thru some buy stops after trading above yesterday’s high before closing right at its 50-day MA. Crop ratings slipped 3% to 54% G/E. Composite ratings fell to a new seasonal low. Ratings fell 8% in NE, 3% in IA and 2% in IL, MO, and SD, areas that saw the heaviest concentration of rain last week. Harvest advanced only 5% to 23%, the slowest pace in 7 years while below the 5-year Ave. of 27%. IA is 7% harvested vs. Ave. of 20% while NE is 15% harvested vs. 24% Ave. The Bloomberg survey shows traders expect US corn production will slip 66 mil. bu. to 15.734 bil. with yields falling .7 bpa to 177.8 bpa. Ending stocks are expected to increase 127 mil. bu. to 1.694 bil. driven by higher supplies from the 2025/26 crop. My production estimate is 15.710 bil. bu. with an average yield of 177.5 bpa. I’ve got ending stocks pegged at 1.695 bil. Census shipments in Aug-26 reached 292 mil. bu., a record high for the month, bringing 2025/26 MY exports to 3.423 bil., 2 mil. below the current USDA forecast. EU 2026/27 corn imports as of Oct. 4th at 5.44 mmt are up 32% YOY.
SOYBEANS
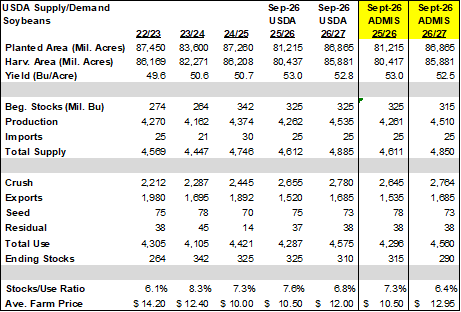
Prices were higher across the complex surging to session highs at the close. Beans were up $.18-$.22, meal was $7-$8 higher while oil was up 45-55 points. Spreads also firmed across the complex. Speculative traders returned as healthy buyers fueled by a combination of lower US crop ratings and Pres. Trump talking up Chinese purchases of US agricultural products at a campaign stop in Nebraska yesterday. Cash sources suggest China was seeking US offers off the Gulf and PNW enabling Nov-26 beans to close back above $13. Near term resistance is the contract high at $13.35 ¼ with support at the 50-day MA at $12.60 ¼. Support for Dec-26 meal is at $341.30 with resistance at $376.90. $.70 has put a lid on Dec-26 oil rallies so far this week. Crop ratings slipped 1% to 57% G/E. Composite ratings fell to a new seasonal low while still just above the historical average. Ratings fell 9% in NE, 6% in MI, and 4% in IA and KY. Harvest advanced only 8% to 25%, also the slowest in 7 years and below the 5-year Ave. of 33%. The Bloomberg survey shows traders expect US soybean production will increase 3 mil. bu. to 4.538 bil. with yields up .1 bpa to 52.9 bpa. Ending stocks are expected to slip 1 mil. bu. to 309 mil. My production forecast at 4.510 bil. bu. and yield at 52.5 bpa are at the lower end of the range. Same with my ending stocks forecast at 290 mil. bu. Abiove reports Brazil’s crush capacity rose 13% in 2026 to 86.4 mmt annually. They forecast total crush in 2026 will reach 63.5 mmt. The USDA crush forecast for the 2026/27 MY is 65 mmt. US census soybean shipments in Aug-26 at 54 mil. bu. brings 2025/26 MY exports to 1.535 bil., 15 mil. above the current USDA forecast. EU soybean imports as of Oct. 4th at 3.06 mmt are down 9% YOY. Meal imports at 4.4 mmt are down 22%.
WHEAT
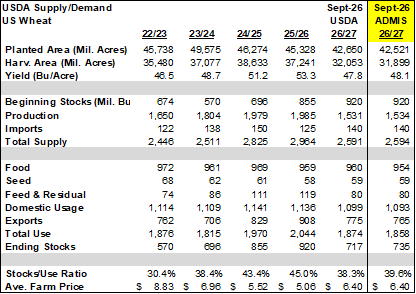
Prices ranged from $.11-$.14 higher in choppy, 2-sided trade. CGO Dec-26 was up $.12 at $7.04 ¼, Dec-26 KC was $.14 higher at $7.56 ¼, while Dec-26 MIAX was up $.11 ¼ at $7.19 ¾. Although the Russia/Ukraine war continues to intensify, according to IKAR Russia was able to export 2.4 mmt of wheat in Sept-26, with a record 1 mmt moving through Baltic ports. Total shipments July-26 through Sept-26 were 6.4 mmt vs. 11.3 mmt YA. IKAR also reports the export price for wheat ended last week at $266/mt FOB, down $1 from the previous week. Ukraine’s agricultural exports through the Danube River ports totaled 1.145 mmt in September, up from 716k in August. US winter wheat plantings advanced 9% to 36%, below the 5-year Ave. of 46%. 16% of the crop has emerged vs. the 5-year Ave. of 20%. The Bloomberg survey shows traders expect US 2026/27 ending stocks will rise 5 mil. bu. to 722 mil. vs. my estimate of 735 mil. bu. Census shipments in Aug-26 at 76 mil. bu. bringing June-Aug sales to 192 mil. bu. down 23% from YA. To reach the current USDA export forecast of 775 mil. bu., shipments Sept. thru May will need to reach 583 mil. bu. vs. the 5-year Ave. of 576 mil. I look for the USDA to lower their export forecast by 10 mil. bu. EU soft wheat exports as of Oct. 4th at 7.52 mmt are up 1% from YA.
Risk Warning: Investments in Equities, Contracts for Difference (CFDs) in any instrument, Futures, Options, Derivatives and Foreign Exchange can fluctuate in value. Investors should therefore be aware that they may not realise the initial amount invested and may incur additional liabilities. These investments may be subject to above average financial risk of loss. Investors should consider their financial circumstances, investment experience and if it is appropriate to invest. If necessary, seek independent financial advice.
ADM Investor Services International Limited, registered in England No. 2547805, is authorised and regulated by the Financial Conduct Authority [FRN 148474] and is a member of the London Stock Exchange. Registered office: 3rd Floor, The Minster Building, 21 Mincing Lane, London EC3R 7AG.
A subsidiary of Archer Daniels Midland Company.
© 2021 ADM Investor Services International Limited.
Futures and options trading involve significant risk of loss and may not be suitable for everyone. Therefore, carefully consider whether such trading is suitable for you in light of your financial condition. The information and comments contained herein is provided by ADMIS and in no way should be construed to be information provided by ADM. The author of this report did not have a financial interest in any of the contracts discussed in this report at the time the report was prepared. The information provided is designed to assist in your analysis and evaluation of the futures and options markets. However, any decisions you may make to buy, sell or hold a futures or options position on such research are entirely your own and not in any way deemed to be endorsed by or attributed to ADMIS. Copyright ADM Investor Services, Inc.
