Written Commentary
CORN
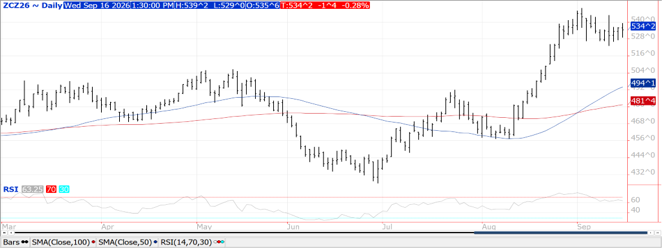
Prices were $.01-$.02 lower closing near the midpoint of the session’s range. Spreads were mixed and little changed. Initial support for Dec-26 is at LW’s low at $5.23 ¼. Corn bulls remain hopeful the Trump/Xi meeting will result in China’s purchase of US corn. Yesterday Conab raised their 2025/26 corn production forecast for Brazil 1.1 mmt to 144, above the USDA forecast of 141 mmt. They estimate production in 26/27 will rise to 148 mmt, well above the USDA est. of 139 mmt. New crop plantings have reached 22% vs. 17% YA. Friday’s COF report is expected to show feedlots held 11.279 mil. head of cattle as of Sept. 1st, up 1.8% from YA. Placements in Aug-26 are expected to be down 3.2% from YA while marketings off 3.9%. Ethanol production held steady at 323 mil. gallons while up 4% YOY. Production was just above the pace needed to reach the USDA 2026/27 corn usage estimate of 5.60 bil. bu. There was 108 mil. bu. of corn used in the production process, or 15.4 mil. bu. per day, an annualized pace of 5.625 bil. bu. Stocks held at 25.2 mil. barrels, well above 22.6 mb from YA. Tomorrow’s export sales are expected to range from 28-78 mil. bu.
SOYBEANS
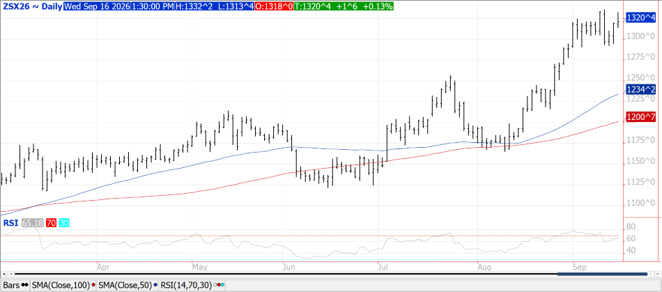
Prices were mixed with beans $.02-$.04 higher, meal was mixed and within $1 of unchanged while oil was down 60-70 points. Bean and oil spreads weakened, while meal spreads firmed. Early strength in Nov-26 beans saw prices come within 3 cents of its contract high of $13.35 ¼. Oct-26 meal jumped out to a fresh 2 ½ year high before backing up. A 3rd consecutive day with no flash sales likely weighed on prices in early trade. Crush margins were little changed at $2.50 bu. while soybean meal PV increased to 51.2%, a 7-month high. Forecasts call for continued heavy rain across the N. Midwest and ECB over the next 7 days, slowing crop maturation and harvest activities. Hot and dry across the S. Midwest and Delta region, helpful for harvest progress. Yesterday Conab forecast Brazil’s 2026/27 soybean acres would grow .7%, the lowest growth in 20 years, to 49.3 mil. HA, with production at 181.6 mmt, well below the USDA est. of 186 mmt. NOPA crush in Aug-26 at 205.5 mil. bu. was below expectations, however still a record high for the month. Implied census crush at 211 mil. bu. brought 25/26 crush to 2.647 mil. bu., 8 mil. shy of the USDA forecast of 2.655 bil. The daily crush rate fell to a 12 month low at 6.81 mbd. Oil stocks slipped to 1.201 bil. lbs. down 11.7% from July and the lowest since Nov-24. Stats Canada forecast canola production at 22.05 mmt, slightly above expectations, while down from 22.23 YA. The trade remains hopeful that US/China will drop reciprocal tariffs at next week’s Trump/Xi summit in Washington. Tomorrow’s export sales are expected to range from 32-88 mil. bu., meal 150-600k tons and oil -10 – 10k tons.
WHEAT
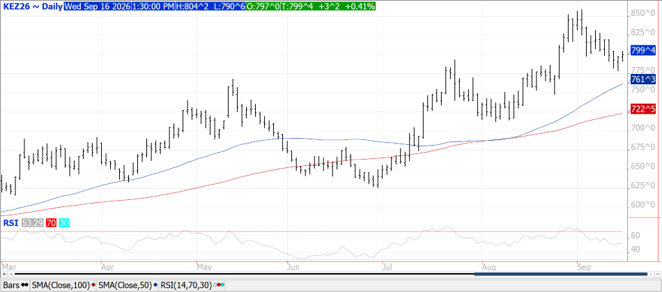
Prices surged late to close higher across the three classes. CGO Dec-26 was up $.02 ¼ at $7.30 ¾, KC Dec-26 was $.03 ¼ higher at $7.99 ½, while Dec-26 MIAX was $.07 ½ higher at $7.56. Stats Canada forecast all wheat production at 36.1 mmt, in line with the USDA while down from 40 mmt YA. SovEcon reports “the prolonged disruption (of feed grains from the Black Sea) is being substantially underpriced, with no clear path to normal shipping.” They forecast July thru Sept wheat shipments from Ukraine/Russia combined will only reach 8 mmt, vs. 16.2 mmt YA and the 5-year Ave. of 18.2 mmt. Ukraine’s WW seedings have reached only 3.3%. So far 171.6k HA of winter grain has been seeded, down 35% from YA. Russian lowered their wheat export duty 2% to 1,146 rubles/mt for the period of Sept. 16-22nd. Yesterday Algeria reportedly bought around 500k mt of optional origin milling wheat near $320/mt CF. Sources suggest Romania and Bulgaria likely the main supplier, however, could include N. Europe, possibly some Russian wheat from the Baltic region. The lowest offer for Pakistan’s 750k mt tender is reported just under $349/mt, which may take a few days to announce results.
Risk Warning: Investments in Equities, Contracts for Difference (CFDs) in any instrument, Futures, Options, Derivatives and Foreign Exchange can fluctuate in value. Investors should therefore be aware that they may not realise the initial amount invested and may incur additional liabilities. These investments may be subject to above average financial risk of loss. Investors should consider their financial circumstances, investment experience and if it is appropriate to invest. If necessary, seek independent financial advice.
ADM Investor Services International Limited, registered in England No. 2547805, is authorised and regulated by the Financial Conduct Authority [FRN 148474] and is a member of the London Stock Exchange. Registered office: 3rd Floor, The Minster Building, 21 Mincing Lane, London EC3R 7AG.
A subsidiary of Archer Daniels Midland Company.
© 2021 ADM Investor Services International Limited.
Futures and options trading involve significant risk of loss and may not be suitable for everyone. Therefore, carefully consider whether such trading is suitable for you in light of your financial condition. The information and comments contained herein is provided by ADMIS and in no way should be construed to be information provided by ADM. The author of this report did not have a financial interest in any of the contracts discussed in this report at the time the report was prepared. The information provided is designed to assist in your analysis and evaluation of the futures and options markets. However, any decisions you may make to buy, sell or hold a futures or options position on such research are entirely your own and not in any way deemed to be endorsed by or attributed to ADMIS. Copyright ADM Investor Services, Inc.
